
PAKISTAN – ROAD MAP TO HOUSING FINANCE
Introduction
Road Map to housing finance has become a national imperative in Pakistan, where a growing population, rapid urbanization, and a massive housing deficit have created urgent demand for affordable homes. With over 10 million housing units needed to meet current demand, and only a fraction of low- and middle-income families able to access formal housing finance, the country stands at a critical juncture. A clear, actionable, and inclusive road map to housing finance is not just a policy document—it is a strategic blueprint for economic growth, social equity, and urban stability.
This summary explores the key components of a viable road map to housing finance, analyzing existing challenges, successful models, financial innovations, and the roles of government, private sector, and civil society in transforming Pakistan’s housing landscape.
Understanding the Housing Crisis
Road Map to housing finance must begin with a realistic assessment of the housing crisis in Pakistan. The country’s urban population is growing at nearly 3.4% annually, one of the highest rates in South Asia. Millions migrate from rural areas to cities in search of jobs, education, and better living conditions. However, the formal housing sector has failed to keep pace, leading to the proliferation of informal settlements—katchi abadis—where over 40% of urban dwellers live. These settlements lack basic services such as clean water, sanitation, and secure tenure. Homes are often self-constructed with temporary materials, vulnerable to fire, flooding, and demolition. The absence of legal titles prevents residents from accessing credit, locking them into cycles of poverty. A comprehensive road map to housing finance must address not only the construction of homes but also the financial systems that enable ownership, security, and upward mobility.The Current State of Housing Finance
Road Map to housing finance reveals that the formal financial sector in Pakistan remains largely inaccessible to low- and middle-income households. Traditional mortgage systems require high down payments (20–30%), stable income documentation, and collateral—conditions that most low-income families cannot meet. As a result, less than 5% of the population has ever accessed a housing loan. Commercial banks focus on high-return, low-risk clients, often ignoring the vast potential of the affordable housing market. Interest rates on housing loans remain high (12–18% annually), and loan tenures are often too short to make repayments manageable. Without a structured road map to housing finance, these systemic barriers will continue to exclude millions from homeownership.Government Initiatives and Policy Frameworks
A critical component of the road map to housing finance is government leadership. The Naya Pakistan Housing Program (NPHP), launched in 2019, represents the most ambitious attempt to create a national framework for affordable housing. The program aims to deliver 5 million homes over a decade through public-private partnerships, land allocation, and financial subsidies. Under NPHP, the government provides land and infrastructure, while private developers construct homes. Buyers receive long-term financing at reduced interest rates, with partial subsidies from the state. This model reflects a key principle of the road map to housing finance: shared responsibility between public and private sectors. Additionally, the State Bank of Pakistan (SBP) has introduced regulatory incentives for banks to increase lending to low-income housing projects. These include risk-sharing facilities, relaxed capital adequacy requirements, and priority sector lending targets. These measures are essential steps in the road map to housing finance, encouraging financial institutions to serve underserved markets.Innovative Financing Models
A successful road map to housing finance must go beyond traditional mortgages. One of the most promising innovations is incremental housing finance, which allows families to build their homes in stages. Loan disbursements are tied to construction milestones—foundation, walls, roof—aligning with the borrower’s cash flow and reducing default risk. Another model is rent-to-own schemes, where tenants gradually acquire ownership through monthly payments that contribute to both rent and equity. This approach is particularly effective for low-income families who cannot afford a lump-sum down payment. These alternative models are central to the road map to housing finance, offering flexibility and realism. Microfinance institutions (MFIs) like Khushhali Microfinance Bank and First Women Bank have also pioneered small housing loans for home improvement—adding roofs, toilets, or walls. While these are not full home loans, they represent a practical entry point in the road map to housing finance for the poorest households.The Role of Technology and Digital Finance
Technology is reshaping the road map to housing finance. Mobile banking platforms like JazzCash and Easypaisa have brought millions into the formal financial system. Digital credit scoring, powered by AI and alternative data (e.g., mobile usage, transaction history), enables lenders to assess creditworthiness without traditional collateral. Fintech solutions can streamline loan applications, reduce processing times, and lower transaction costs. For example, blockchain-based land registries could resolve title disputes and enable secure property ownership—critical for collateral-based lending. Integrating digital tools into the road map to housing finance is essential for scalability, transparency, and inclusion. Moreover, online platforms can provide financial literacy training, helping low-income borrowers understand loan terms, interest rates, and repayment schedules. A digitally enabled road map to housing finance ensures that financial services reach even the most remote and marginalized communitiesPrivate Sector Engagement and Public-Private Partnerships
The private sector is a key driver in the road map to housing finance. Developers, construction companies, and financial institutions bring capital, expertise, and innovation. However, many remain hesitant to invest in affordable housing due to perceived risks and low profit margins. Public-private partnerships (PPPs) can de-risk investments and attract private capital. Under PPP models, the government provides land, infrastructure, and subsidies, while the private sector handles construction and management. This shared-risk approach is a cornerstone of the road map to housing finance, balancing social impact with financial viability. Blended finance—combining public funds, donor support, and private investment—is another powerful tool. By absorbing part of the initial risk, development agencies and governments can encourage commercial banks to enter the affordable housing market. This model has been successfully used in other developing countries and should be scaled in Pakistan as part of the road map to housing finance.Community-Led and Cooperative Models
A truly inclusive road map to housing finance must include community-led solutions. The Orangi Pilot Project (OPP) in Karachi is a shining example of how low-income communities can organize to build their own homes and infrastructure. Through collective savings and labor, residents constructed sanitation systems and housing with minimal external support. Cooperative housing societies, where members pool resources to buy land and build homes, are another effective model. These societies reduce individual financial burdens and foster social cohesion. The road map to housing finance should support such grassroots initiatives through technical assistance, low-interest loans, and legal recognition. By empowering communities, the road map to housing finance shifts from a top-down approach to a participatory one—ensuring that beneficiaries are not passive recipients but active agents of change.Gender Inclusion in Housing Finance
A critical yet often overlooked aspect of the road map to housing finance is gender equity. In Pakistan, property ownership is predominantly in male names, making it difficult for women to access housing loans. Yet, studies show that women are more likely to invest in home improvements, children’s education, and healthcare. Programs like First Women Bank and Kashf Foundation have demonstrated that women are reliable borrowers and effective managers of housing investments. The road map to housing finance must include gender-responsive policies—such as joint titling, women-only loan products, and financial literacy programs—to ensure that half the population is not left behind.Addressing Land Tenure and Legal Barriers
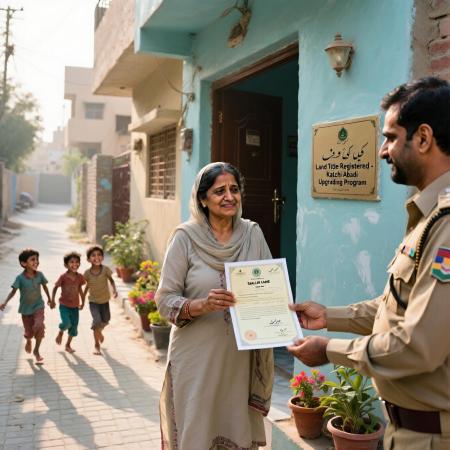
One of the biggest obstacles in the road map to housing finance is insecure land tenure. Millions live on state-owned or illegally occupied land, meaning they cannot use their homes as collateral. Millions live without security of tenure, meaning they lack legal recognition of their right to occupy or improve their homes—blocking access to finance and basic services. The road map to housing finance must include slum upgrading and land regularization programs. By formalizing informal settlements and issuing titles, governments can unlock access to credit and public services. Cities like Lahore and Karachi have begun mapping katchi abadis using GIS technology—a vital first step in the road map to housing finance. Legal reforms are also needed to simplify property registration, reduce corruption, and protect tenant rights. Secure tenure is not just a legal issue—it is the foundation of financial inclusion.Scaling Up Financial Literacy and Awareness
Even when housing finance products exist, many low-income families do not understand how they work. Fear of debt, mistrust of banks, and lack of financial knowledge prevent uptake. A successful road map to housing finance must include nationwide financial literacy campaigns. These campaigns should use local languages, community leaders, and digital platforms to educate people about savings, credit, and loan management. Schools, mosques, and mobile networks can serve as delivery channels. When people understand the benefits and risks of housing finance, they are more likely to participate.Monitoring, Evaluation, and Data Systems
A robust road map to housing finance requires strong data systems and performance tracking. Currently, data on housing conditions, loan disbursements, and repayment rates is fragmented or outdated. Without reliable information, policymakers cannot assess what works and what doesn’t. The road map to housing finance should establish a national housing finance database, integrating data from banks, MFIs, developers, and government agencies. Regular monitoring and impact evaluations will ensure accountability and continuous improvement.International Cooperation and Funding
International development partners—such as the World Bank, Asian Development Bank (ADB), and UN-Habitat—have a vital role to play in supporting the road map to housing finance. They provide funding, technical expertise, and policy guidance for housing and urban development projects. For example, ADB-supported programs have helped pilot affordable housing finance models in Punjab and Sindh. These partnerships can be expanded to scale up successful initiatives. The road map to housing finance should leverage international cooperation to attract investment, share best practices, and build institutional capacity.The Path Forward: Key Recommendations
To realize the full potential of the road map to housing finance, Pakistan must take the following actions:- Expand access to long-term, low-interest housing loans for low- and middle-income families.
- Scale up incremental and rent-to-own financing models.
- Strengthen land titling and slum regularization programs.
- Promote digital finance and fintech innovation.
- Support community-led and cooperative housing initiatives.
- Ensure gender inclusion in all housing finance programs.
- Invest in financial literacy and public awareness.
- Enhance coordination between federal, provincial, and local agencies.