

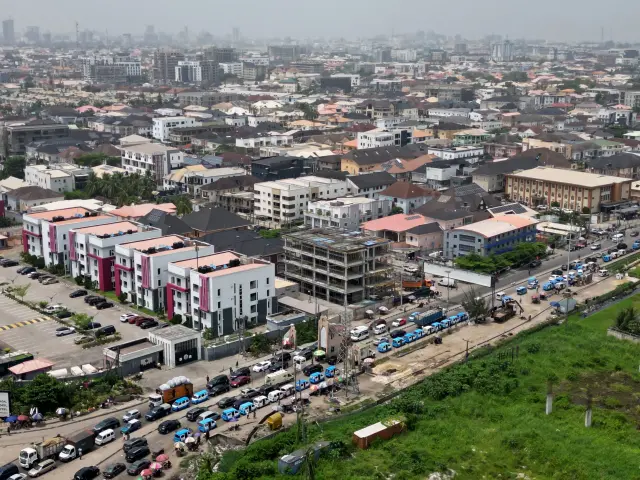
What’s the Best Financing Model for Affordable Housing in Nigeria?
Nigeria, the most populous country in the African continent is in the acute housing shortage, as it requires more than 17 million units to serve the increasing urban population. Homeownership has been an elusive dream to many Nigerians due to rapid urbanization population increase and the skyrocketing housing prices.
 Housing is becoming a very important policy and
economic issue, which requires new financing mechanisms that can help to
balance the demand and supply.
In the past, the development of housing in Nigeria has been dependent on the interventions of government and the private developers. The regular means of financing however, direct government funding or traditional mortgage loans have not worked because they are very expensive, have limited scopes and are bureaucratic.
The dilemma is how to develop financing schemes
which are sustainable, affordable as well as responsive to the socio-economic
condition of the Nigeria households.
An effective affordable housing finance model should take into account the income inequalities, inflation, interests, and ability of the citizens to repay the loans. It must also encourage the participation of the private sector but be socially equitable.
This blog discusses the most feasible
financing models to affordable housing in Nigeria, how they have been
effective, their challenges, and how best they can offer a solution that is
long-term.
The six main models that will be discussed are Government-Subsidized Housing, Public-Private Partnerships (PPP), Mortgage Financing, Cooperative Housing Schemes, Microfinance Models and International Funding and Development Agencies.
Each of the models is considered with regards
to feasibility, scalability, and fit to the Nigerian housing market. At the
conclusion of this discussion, it will be seen that which financing models
would provide the most sustainable options to resolving Nigeria affordable housing
crisis.
Housing with Government subsidies
The most conventional way of solving the housing shortages is probably the government-subsidized housing. Under this type of model, the government bears a huge part of the cost which may be in the form of offering land, construction finances, or interest-free loans to the citizens.
The main
aim is to ensure that the low and middle income earners who would not afford
the homes at the market rates are made to access housing.
In Nigeria, the Federal Mortgage Bank of Nigeria (FMBN) and the National Housing Fund (NHF) are agencies which have traditionally tried to provide affordable housing. The subsidies may be in various forms such as lower-cost construction materials, developers tax incentives or cash grant to potential homeowners.
The benefit associated with this model is that this model
guarantees inclusion with vulnerable populations that may not be targeted by
the private developers.
Nevertheless, there are major challenges with the government-subsidized housing. Limitation of the project size due to budgetary uncertainties is common and scam and bureaucracy may slow down the construction process.
Also, urban centers are occasionally considered to the detriment of
rural communities, further increasing the housing disparities in the regions.
Nonetheless, subsidies continue to play a significant role when it is used
together with other sources of financing including involving private developers
or using international sources of finance.
In the case of Nigeria, a sustainable model of government subsidized housing needs to be transparent, the allocation of resources in a way that is strategic and mechanisms that work towards ensuring that there are no distortions in the market.
Nigeria can increase affordability of housing by
adopting intelligent subsidy measures; that is, matching the amounts paid by
citizens to the government or introducing partial forms of subsidies depending
on the income level.
Public-Private Partnerships (PPP)
A possible solution to this restriction of government-funded housing projects has been developed: Public-Private Partnerships (PPP). This model takes advantage of the efficiency of the private sector, capital and innovation and still has government control and regulation.
With a PPP
structure, a government may usually offer land or initial capital, and the
design and building and occasionally financing is done by private developers.
Nigeria has used PPP models in projects such as the Lagos State Home Ownership Mortgage Scheme where developers are urged to develop affordable units but give long term mortgage to residents.
The strength of PPPs
is that they help in the mobilization of the private capital, shaving down of
the fiscal burden of the government, and project timelines are saved. Also,
technology and management practices that enhance the quality and sustainability
of housing projects are usually introduced by the private developers.
They include the alignment of the agenda of the public and
private stakeholders. Private firms can focus on their profitability which may
make the housing units unaffordable. To balance profitability and social
objectives, there must be clear contractual agreements, government incentive
like tax breaks or support of infrastructure and strict regulatory frameworks.
In the case of Nigeria, housing deficit can be solved
through PPP. Through proper organization, the government can lure the interest
of the private investors without affecting the affordability. The trick is in
coming up with clear, responsible and win-win deals that guarantee access and
quality.
Mortgage Financing
In most developed economies, mortgage financing has formed
the basis of housing development as it gives long-term loans to people who
cannot meet the cost of buying houses outright. The penetration of mortgage is
low in Nigeria, mainly because of high rates of interest rates, short term
loans and lack of publicity.
Mortgage products are availed through the National Housing Fund scheme by the Federal Mortgage Bank of Nigeria and commercial banks. This system collects the money of donors and reinvests it as long term mortgage loans to buy or construct homes.
The mortgage financing enables people to pay
over a period of years or decades making the owning of a house affordable to
middle-income earners.
Issues such as affordability, since interest rates are usually above 15 percent, and loan terms are also low relative to the international ones can be considered as a challenge. The lack of culture of extended credit is also an obstacle to taking up mortgages.
In order to deal
with these hitches, Nigeria can establish risk-sharing systems, interest rate
subsidies and long-term payment plan. Besides, electronic mortgage websites can
minimize transaction expenses and enhance availability to a broader cohort.
Government support or PPP programs with mortgage financing
may be a successful model of affordable housing which is scalable. Through
incentives to banks as well as homebuyers, this model can help close the
disparity between high demand and low involvement of the private sector.
Cooperative Housing Schemes
The co-op housing models are based on communal effort in
sharing resources in acquiring and developing residential units. Members make
investments to a shared fund to which they contribute money that can be used to
build houses or purchase estates. This model is focused on the involvement of
the community, social integration and cost-sharing, eliminating the need to use
external funds.
In Nigeria, cooperative societies have in the past contributed to urban and semi-urban housing development. Some of the benefits are that the cost will be reduced, there will be shared responsibility, and the traditional financing limitations will be avoided.
The community engagement and
long-lasting ownership, which are promoted by cooperative models also lower the
challenges such as house abandonment or mismanagement.
But cooperative housing has to have good governance to prevent conflicts, mismanagement and corruption. Laws should be transparent on how the funds are managed and the allocation of the housing units should be fairly distributed.
Also, collaborative plans can find it difficult to grow
because they do not have access to large volumes of capital and technical
skills.
In Nigeria, cooperative housing can be used to supplement
government and private efforts to provide affordable housing. Through pooled
resources and technical assistance provided by banks or developers, cooperative
models are capable of providing low cost, culturally sensitive housing
alternatives that are based on the affordability of middle and low income
Nigerians.
Microfinance Models
Microfinance has transformed accessibility to small-scale loans among the low-income groups of the people in Africa. Microfinance institutions (MFIs) in the housing sector offer small, short-term credits that enable households to construct step by step, acquire materials or make improvements on the current constructions.
This model would be in line with the
reality of informal settlements in which families might not be able to afford
large mortgages but can undertake small monthly payments.
The microfinance banks in Nigeria have also come up with a housing loan program of a few thousand to one or two million naira. These are loans where the terms of repayment are flexible and the capital requirement is small and hence accessible to the informal sector workers.
Gradually increased
housing through microfinance is used to enable families to increase their
housing size and condition as income grants access and reduces the initial
cost, with the benefits of improved living conditions over time.
The problems are high interest rates as compared to
conventional mortgages, loan limits, and operational limitations to MFIs. In
order to add effectiveness, collaborations with government agencies,
non-governmental organizations and foreign donors may offer guarantees,
subsidies and technical support. Also, the efficiency, transparency, and reach
could be improved when digital financial services are integrated.
Microfinance schemes, especially incremental housing
schemes, offer a viable way of helping the low-income earners in Nigeria to get
access to traditional mortgages. They also promote financial discipline and
culture of home ownership, which is critical in sustainable development of
housing.
International Funding Agencies and Development Agencies
Donor organizations and international development agencies
are imperative in aiding the affordable housing projects in the developing
countries. The World Bank, African Development Bank, and UN-Habitat are some of
the organizations that give out grants, low-interest loans, and technical
skills to governments and privately owned developers.
International funding has also facilitated massive houses
constructions, capacity building and urban planning in Nigeria. Such agencies
tend to apply new forms of financing such as blended finance which involves the
mixture of grants, concessional loans, and private investment to minimize risks
and improve the viability of projects.
The advantages of international participation are that it
entails access to best practice, long term technical assistance and that of
leveraging large scale investment. Policy reforms, housing finance frameworks
and affordability can also be achieved through these partnerships.
There are however, dangers of dependence on external funding. Bureaucratic situations, currency exchange rates, and donor preferences that might not be in total accordance with the local requirements can result in project delays.
The models of sustainability dictate that the
international assistance should supplement the domestic efforts at the expense
of eliminating them.
A hybrid model of international financing, government policies, public-private partnerships (PPPs) as well as domestic financing in Nigeria is a holistic solution to affordable housing. This model is replicable and sustainable relying on the best practices in the world and empowering the local stakeholders.
It will facilitate access to a broader audience, be viable
in the long-term, and implement successfully since it will combine various
sources of funding and apply local knowledge, which will provide a system that
will solve the problem of housing shortage and social-economic realities of the
Nigerian population.
Innovative Financing Models and Technology-Driven Solutions
Since Nigeria has a large housing deficit, conventional means of finance might not be enough. Emerging forms of innovative finance, which are frequently accompanied by technological solutions, are becoming viewed as crucial mechanisms of filling the affordable housing gap.
The
strategies utilize the current financial products, online platforms, and data
analytics to provide better access and lower costs and efficiency in the
housing delivery.
A new trend is what is recommended as crowd funding to housing, where numerous investors put small funds to finance residential programs. Digital platforms allow transparency, real-time investment monitoring, and direct interaction between the developers and the contributors.
Crowdfunding will eliminate the dependency on big institutional lending and
democratize access to housing finance, which will enable middle- and low-income
Nigerians to engage in real estate development.
The other innovation is the digital mortgage and payment platforms. Nigeria Fin techs are simplifying the process of applying a mortgage, offering flexible repayment terms, and micro lending to build or renovate a home with the help of mobile applications.
These channels cut down
paper work, administrative delays and expand financial services to underserved
communities especially those in rural and semi-urban communities.
Housing finance is also becoming a revolution of block chain technology. It is able to enhance land ownership, title registration, and property transactions, which will diminish fraud and provide safe lending.
Increased trust between lenders, developers and homeowners is introduced
through smart contracts which automate payment schedules and make sure that the
contractual obligations are met.
Also, green financing models are being considered, by which
the money would be invested into sustainable and energy-efficient houses. These
models tend to receive concessional financing in the international sites by the
international agencies and other environmental conscious investors to ensure
that the cost of construction is subsidized on a long term basis and
environmental sustainability is encouraged.
Through these new methods of innovation, Nigeria can be able to supplement current financing systems such as PPPs, microfinance and cooperative housing.
The solutions that are technology-based make accessibility
and transparency better but also enable citizens to engage directly in housing
development. These models can turn affordable housing into a reality that will
be achieved by millions of Nigerians as the country adopts fin tech and digital
innovation.
Conclusion
The affordable housing issue in Nigeria is complex in nature
and needs a blend of unique financing concepts as dictated by economic, social
and demographic realities in the country. The magnitude of demand cannot be
covered by only one model, however, strategic combination of several strategies
can provide stable solutions.
Government subsidies on housing directly assist low-income citizens whereas PPPs use the efficiency and capital of the private sector to deliver faster. Mortgage financing provides affordability in the long run to the middle-income population, and cooperative housing encourages community involvement and cost-sharing.
Microfinance facilitates incremental housing to
the low-income earners and the international funding also injects capital,
expertise and new innovative financing structures.
The most promising is a hybrid model that will integrate these strategies. As an example, mortgage interest rates could be lowered by the government, timely construction could be guaranteed by the PPPs, and incremental growth could be facilitated by the microfinance schemes.
The social
cohesion can be developed with the help of cooperative models, and technical
guidance and risk mitigation is offered through international assistance.
Finally, the effectiveness of any financing model depends on good governance, transparency, and in accordance with the income abilities of the citizens.
To ensure that affordable housing is not a mere policy objective
but a reality that is enjoyed by millions of people in Nigeria, Nigeria needs
to focus on long-term policy consistency, regulatory changes, and strategic
alliances.
The housing gap in Nigeria can be bridged, economic growth spurred, and all its citizens provided with safe, adequate, and affordable homes through an innovative approach in terms of financing, a deliberate policy will close this gap.
The combination of different sources of financing is the
roadmap of a world in which affordable housing is possible, sustainable and
affordable.
Also read: Urban Renewal Programs in Nigeria: How They Address Slums














LEAVE A REPLY