

utah-s-homeownership-affordability
Boosting Utah’s Homeownership Affordability
Introduction
Utah stands at a critical juncture in its housing landscape, where rapid population growth has collided with constrained housing supply to create one of the nation's most pressing affordability challenges. Despite maintaining a relatively strong homeownership rate of 68.3 percent in 2024—slightly above the national average—the path to homeownership has grown increasingly steep for middle-income families, young professionals, and first-time buyers across the Beehive State.
Boosting Utah's Homeownership Affordability requires a multifaceted strategy that addresses supply constraints, financial barriers, regulatory frameworks, and long-term sustainability. This comprehensive approach must balance market realities with intentional policy interventions to ensure that the American dream of homeownership remains accessible to current and future generations of Utahns.
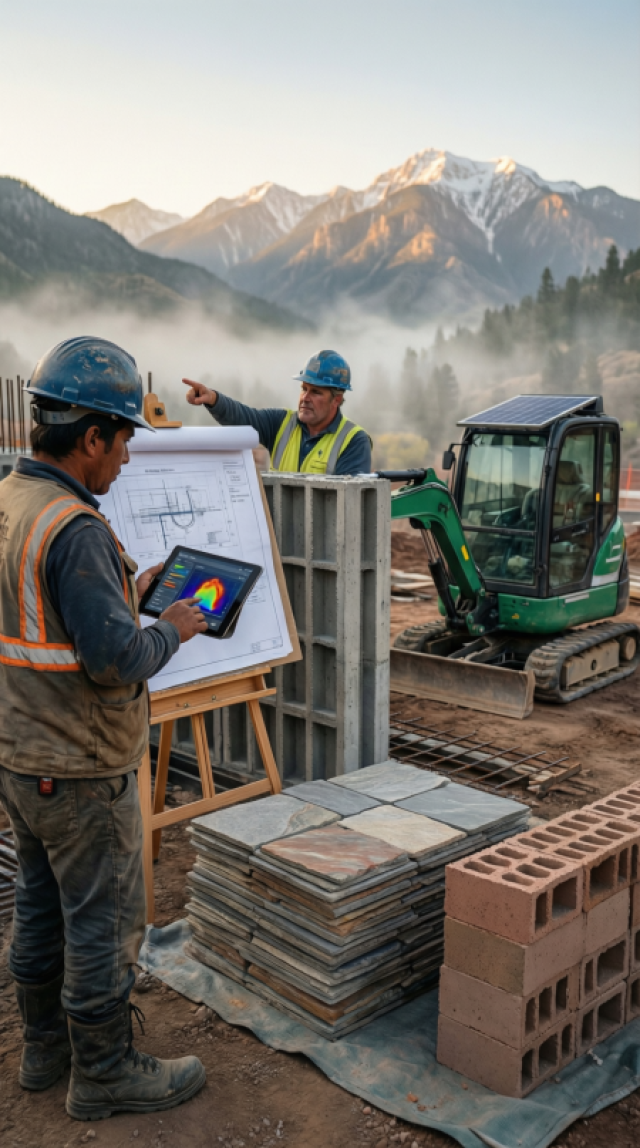 Boosting Utah's Homeownership Affordability Through Supply-Side Interventions
The foundation of Utah's affordability crisis rests on a fundamental imbalance between housing demand and supply. The state's population has grown at nearly twice the national rate over the past decade, yet housing production has failed to keep pace. Researchers project a shortage of 153,000 homes by 2030 if current construction trends continue, with some analyses suggesting an even more sobering deficit of 235,000 units over thirty years without significant policy changes. Boosting Utah's Homeownership Affordability begins with accelerating housing production, particularly in the missing middle category of starter homes priced between $300,000 and $500,000.
Governor Spencer Cox's administration has committed to constructing 35,000 starter homes alongside 150,000 total new housing units by 2028, representing the most ambitious state-led housing production goal in recent memory. However, builders face persistent obstacles, including labor shortages, escalating land acquisition costs, and municipal zoning restrictions that limit density in established neighborhoods.
Boosting Utah's Homeownership Affordability demands zoning reform that permits accessory dwelling units, duplexes, triplexes, and modest multifamily developments in areas traditionally reserved for single-family homes.
Recent legislative efforts, including HB 37, have introduced density overlay provisions allowing municipalities to approve up to 20 percent more units than normally permitted under existing zoning, though implementation remains voluntary at the local level. Without consistent density allowances across Utah's fastest-growing counties, supply constraints will continue exerting upward pressure on home prices.
Boosting Utah's Homeownership Affordability with Targeted Financial Assistance
Even as supply-side solutions take years to materialize, immediate relief for aspiring homeowners requires robust financial assistance programs. Utah Housing Corporation operates several down payment assistance initiatives, including First Home, Home Again, and Score programs that provide qualified buyers with up to $20,000 toward down payments, closing costs, or interest rate buydowns. These programs specifically target first-time homebuyers earning at or below 120 percent of area median income, though some options remain available to repeat buyers in targeted census tracts.
Boosting Utah's Homeownership Affordability also involves leveraging federal resources through the Housing Trust Fund, which channels dollars toward developing deeply affordable units for extremely low-income households. Salt Lake County and Salt Lake City maintain their own municipal housing trust funds that finance preservation and new construction of affordable units, though funding levels remain insufficient relative to documented need.
The National Low Income Housing Coalition estimates Utah requires 48,000 additional affordable rental homes to serve extremely low-income residents, highlighting the interconnected nature of rental and ownership markets. When rental affordability deteriorates, potential first-time buyers remain trapped in leasing arrangements, unable to accumulate savings for down payments. Boosting Utah's Homeownership Affordability therefore requires parallel investments in both rental assistance and ownership pathways.
Boosting Utah's Homeownership Affordability by Addressing Price-to-Income Imbalances
Utah's housing affordability metrics reveal troubling disparities between home values and household earnings. The state ranked ninth most expensive nationally in 2024, with a median home price of $547,700 against a median household income of approximately $91,750—a price-to-income ratio exceeding 5.6. Financial advisors traditionally recommend ratios below 3.0 for healthy housing markets, meaning Utah families must devote substantially more income toward housing costs than historical norms suggest is sustainable.
Boosting Utah's Homeownership Affordability requires acknowledging that high nominal incomes alone cannot resolve affordability challenges when home prices escalate faster than wage growth. While Utah boasts one of America's strongest labor markets with median incomes significantly above national averages, the housing cost burden disproportionately impacts service workers, educators, healthcare support staff, and young professionals launching careers.
These essential workers increasingly face commutes exceeding sixty minutes as they seek affordable housing in outlying counties, undermining quality of life and community cohesion. Boosting Utah's Homeownership Affordability demands policy attention to starter home production specifically, as entry-level inventory has virtually disappeared from many Utah markets. New construction has skewed toward luxury segments where profit margins justify escalating land and regulatory costs, leaving a void in attainable housing options for households earning $60,000 to $100,000 annually.
Boosting Utah's Homeownership Affordability Through Regulatory Modernization
Municipal regulations significantly influence housing development feasibility across Utah's diverse communities. Impact fees, lengthy approval processes, parking minimums, and restrictive lot size requirements collectively increase development costs by an estimated $50,000 to $100,000 per unit in many jurisdictions. Boosting Utah's Homeownership Affordability requires state-level leadership to encourage regulatory streamlining while respecting local control.
The Utah Legislature has begun examining preemption strategies that would establish baseline density allowances statewide, potentially overriding municipal restrictions that effectively ban duplexes or townhomes in vast swaths of residential land. While controversial among local officials who value zoning autonomy, such measures reflect growing recognition that hyperlocal control has contributed to regional housing shortages.
Boosting Utah's Homeownership Affordability also involves reforming impact fee structures to ensure they reflect actual infrastructure costs rather than serving as de facto revenue generators for municipalities. Several Utah communities have implemented fee waivers or reductions for developments that include affordable units or target first-time buyers, creating incentives for builders to serve middle-income markets. Additionally, expediting permitting timelines through dedicated housing review staff and digital submission platforms can reduce carrying costs for developers, savings that may translate to modestly lower home prices.
Boosting Utah's Homeownership Affordability with Energy Efficiency Integration
Energy efficiency represents an underutilized lever for improving long-term housing affordability in Utah's climate. Homes built to modern efficiency standards—including enhanced insulation, high-performance windows, and efficient HVAC systems—typically command $15,000 to $30,000 premiums upfront but generate substantial monthly savings through reduced utility bills. Boosting Utah's Homeownership Affordability through efficiency standards effectively lowers the total cost of homeownership even when purchase prices remain elevated.
Utah's strategic housing plan explicitly recognizes energy efficiency as a critical affordability component, encouraging adoption of updated building codes that improve thermal performance without dramatically increasing construction complexity. For existing homeowners facing affordability pressures, weatherization assistance programs administered through community action agencies provide no-cost upgrades to low-income households, reducing energy burdens that often consume 10 to 15 percent of monthly income for vulnerable families.
Boosting Utah's Homeownership Affordability must therefore encompass both production-side efficiency standards and retrofit programs that preserve affordability for current owners facing rising utility costs alongside property tax increases.
Boosting Utah's Homeownership Affordability While Navigating Political Constraints
Utah's political environment presents both opportunities and limitations for affordability interventions. The state constitution prohibits rent control, eliminating one tool available to other states grappling with housing cost escalation. This restriction reflects Utah's generally market-oriented policy framework but places greater emphasis on supply expansion and direct assistance rather than price regulation. Boosting Utah's Homeownership Affordability within this constraint requires creative policy design that works with market dynamics rather than against them.
Tax increment financing districts, infrastructure revolving loan funds, and density bonuses for affordable units represent market-compatible mechanisms that have gained traction among Utah policymakers. Additionally, public-private partnerships between municipal housing authorities, nonprofit developers, and for-profit builders have successfully delivered mixed-income communities in Salt Lake City, Provo, and Ogden. Boosting Utah's Homeownership Affordability demands continued collaboration across partisan lines, as housing shortages affect Republican and Democratic constituents alike across urban, suburban, and rural geographies.
Boosting Utah's Homeownership Affordability for Future Generations
Long-term success in Boosting Utah's Homeownership Affordability depends on intergenerational planning that anticipates demographic shifts and economic transitions. Utah's relatively young population—with a median age significantly below the national average—will generate sustained housing demand for decades. Without deliberate policy intervention, affordability challenges will compound as today's renters age without accumulating home equity.
Boosting Utah's Homeownership Affordability requires normalizing alternative ownership models, including community land trusts, limited-equity cooperatives, and shared equity programs that preserve affordability across resale cycles. These models have gained traction in high-cost coastal markets and offer promising templates for Utah communities seeking to maintain economic diversity amid growth pressures.
Furthermore, integrating affordable housing planning with transit-oriented development near Frontrunner and TRAX stations can reduce transportation costs—a major household expense—while supporting sustainable growth patterns. Boosting Utah's Homeownership Affordability ultimately means creating communities where teachers, firefighters, retail workers, and recent graduates can realistically envision putting down roots without sacrificing financial security or enduring punishing commutes.
Conclusion: A Coordinated Path Forward for Boosting Utah's Homeownership Affordability
The challenge of Boosting Utah's Homeownership Affordability cannot be solved through any single policy lever. Success requires simultaneous progress on multiple fronts: accelerating housing production through zoning reform and regulatory streamlining; expanding down payment assistance and mortgage credit access; preserving existing affordable inventory through targeted acquisition funds; integrating energy efficiency to reduce long-term ownership costs; and fostering public-private partnerships that leverage diverse capital sources.
Utah's strong fiscal position, growing economy, and tradition of pragmatic governance provide advantages absent in many high-cost states. Yet time is of the essence—each year of constrained supply deepens affordability gaps and pushes homeownership further from reach for middle-income households. Boosting Utah's Homeownership Affordability demands sustained political will, cross-jurisdictional coordination, and willingness to challenge longstanding assumptions about neighborhood character and development intensity.
The alternative—a future where homeownership becomes the exclusive domain of six-figure earners—contradicts Utah's cultural values of family stability, community investment, and broad-based prosperity. By embracing comprehensive, evidence-based strategies today, Utah can chart a course toward inclusive growth where boosting Utah's Homeownership Affordability remains an achievable reality rather than an increasingly distant aspiration.
-5yCS4OoVBg.jpg)





LEAVE A REPLY