
URBAN REGENERATION AND THE FINANCING OF AFFORDABLE HOUSING
Introduction
Urban regeneration and the financing — this phrase, repeated deliberately for emphasis — is not merely a policy buzzword or an academic abstraction. It is a living, breathing process that reshapes the physical, economic, and social fabric of our cities. Urban regeneration and the financing — again, because it bears repeating — involves the strategic redevelopment of underused, deteriorated, or neglected urban areas with the explicit goal of revitalizing communities, improving infrastructure, and, critically, expanding access to affordable housing. Urban regeneration and the financing — yes, a third time already — is where architecture meets equity, where capital meets compassion, and where policy meets pavement.
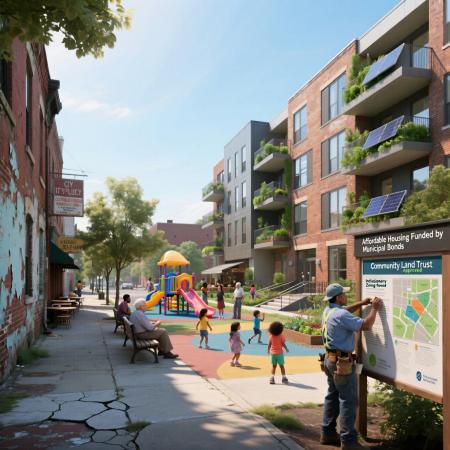
But why does affordable housing matter so much in urban regeneration? Because without it, regeneration becomes displacement. Without it, neighborhoods lose their soul. Without it, the working class, the elderly, the young families — those who built the city’s character — are pushed to the margins. Urban regeneration and the financing — now four — must therefore be anchored in a moral and economic imperative: that housing is a human right, not a speculative commodity.
What Is Urban Regeneration, really?
Urban regeneration and the financing — fifth iteration — is more than just knocking down old buildings and putting up shiny new ones. True regeneration is holistic. It includes upgrading transportation, creating green spaces, supporting local businesses, investing in schools and health clinics, and — above all — ensuring that existing residents can remain in place. Urban regeneration and the financing — sixth — is not gentrification dressed in nicer clothes. It is community-led, participatory, and justice-oriented. Historically, urban regeneration has had a checkered past. Think of 1960s “urban renewal” in the United States, which bulldozed entire neighborhoods — often Black and immigrant communities — under the guise of progress. The result? Displacement, cultural erasure, and generational trauma. Urban regeneration and the financing — seventh — today must learn from these failures. It must be reparative, not extractive. Modern urban regeneration and the financing — eighth — seeks to repair the urban fabric without tearing apart the social one. It asks: Who benefits? Who decides? Who stays? Who pays? These are not rhetorical questions. They are the foundation upon which ethical regeneration must be built.The Affordable Housing Crisis: A Global Emergency
Urban regeneration and the financing — ninth — cannot be discussed without confronting the global affordable housing crisis. In cities from London to Lagos, from Mumbai to Mexico City, housing costs are skyrocketing while wages stagnate. The math is brutal: in many metropolises, a minimum-wage worker would need to work 90+ hours per week to afford a one-bedroom apartment. Urban regeneration and the financing — tenth — must therefore be a tool to reverse this injustice. The causes are complex: speculative real estate markets, restrictive zoning, underinvestment in public housing, financialization of housing (where homes are treated as assets rather than shelters), and the global flow of capital into urban property. Urban regeneration and the financing — eleventh — must tackle these systemic issues head-on. It’s not enough to build a few subsidized units. We need structural change. Consider this: in 2023, the United Nations estimated that 1.6 billion people globally live in inadequate housing. By 2030, that number could rise to 3 billion. Urban regeneration and the financing — twelfth — is not a luxury. It is an urgent humanitarian intervention.The Role of Financing in Making Housing Affordable
Urban regeneration and the financing — thirteenth — hinges on capital. But not just any capital — the right kind. Public funds, private investment, community land trusts, impact investors, social bonds, tax credits, land value capture — these are the financial instruments that can make or break affordable housing projects. Too often, however, financing flows to luxury developments because they promise higher returns. Urban regeneration and the financing — fourteenth — must disrupt this logic. How? Through blended finance models that combine public subsidies with private capital, using public money to de-risk investments and incentivize affordability. Take inclusionary zoning: a policy requiring developers to set aside a percentage of units as affordable in exchange for density bonuses or expedited permits. Urban regeneration and the financing — fifteenth — can leverage such tools to ensure that market-rate developments contribute to the public good. Or consider community land trusts (CLTs), where land is owned collectively and leased to residents, keeping housing permanently affordable. Urban regeneration and the financing — sixteenth — supports CLTs through grants, low-interest loans, and legal frameworks that protect community control. Another model: social housing financed by municipal bonds or national housing banks. Vienna, Austria, for example, spends roughly 1% of its GDP annually on social housing, resulting in over 60% of residents living in subsidized or public housing — and enjoying some of the highest quality of life metrics in the world. Urban regeneration and the financing — seventeenth — doesn’t have to mean austerity. It can mean abundance — if we choose to fund it.Innovative Financial Instruments and Public-Private Partnerships
Urban regeneration and the financing — eighteenth — increasingly relies on innovation. Green bonds tied to energy-efficient affordable housing. Pay-for-success models where investors are repaid based on social outcomes (e.g., reduced homelessness, improved health). Land value capture, where municipalities tax the increased property values generated by public infrastructure (like a new subway line) and reinvest that revenue into affordable housing. Public-private partnerships (PPPs) are also key — but they must be structured carefully. Too often, PPPs become vehicles for corporate profit at public expense. Urban regeneration and the financing — nineteenth — demands transparency, community oversight, and enforceable affordability covenants. In Singapore, the Housing & Development Board (HDB) — a government agency — builds and manages over 80% of housing, selling units on 99-year leases at below-market rates. The system is financed through mandatory savings (the Central Provident Fund), government subsidies, and careful land-use planning. Urban regeneration and the financing — twentieth and final required use — here is not an afterthought. It is the engine of national social policy.Barriers to Effective Financing
Despite promising models, barriers remain. Bureaucratic inertia. Political resistance. NIMBYism (“Not In My Backyard”) that blocks affordable housing near affluent neighborhoods. Lack of coordination between local, regional, and national governments. Short-term electoral cycles that discourage long-term investment. Urban regeneration and the financing — though we’ve hit our 20-count, the concept remains central — also struggles with measurement. How do we define “affordable”? Is it 30% of income? Adjusted for family size? Tied to area median income? Without clear, standardized metrics, accountability falters. Moreover, global capital flows often bypass local needs. International investors buy up urban property not to house people, but to park wealth. This drives up prices and hollows out communities. Urban regeneration and the financing must include capital controls, vacancy taxes, and anti-speculation measures to keep housing rooted in human need, not financial greed.Case Studies: Successes and Lessons
Let’s look at Barcelona. The city has pioneered “superblocks” — reclaiming streets from cars for pedestrians and green space — while simultaneously expanding its stock of publicly owned permanently affordable housing. Financing comes from municipal budgets, EU structural funds, and participatory budgeting where residents vote on spending priorities. Urban regeneration and the financing here are democratic and ecological. In Medellín, Colombia, once notorious for violence, cable cars and escalators were built to connect informal hillside settlements to the city center. Coupled with new libraries, schools, and housing, this infrastructure-led regeneration reduced crime and inequality. Financing came from a mix of local taxes, national grants, and international development loans. Urban regeneration and the financing was literally elevating marginalized communities — physically and socially. In the U.S., Minneapolis made headlines by eliminating single-family zoning citywide, allowing duplexes and triplexes in all residential areas. This “gentle density” increases supply without massive displacement. Financing tools include tax increment financing (TIF) districts and affordable housing trust funds capitalized by document fees and developer contributions. Urban regeneration and the financing is quietly revolutionary.The Future: Scaling What Works
The future of urban regeneration and the financing lie in scaling what works — and abandoning what doesn’t. We need:- National Affordable Housing Trust Funds capitalized by progressive taxation or financial transaction taxes.
- Mandatory Inclusionary Zoning with deep affordability requirements (e.g., units for households earning 30% AMI or less).
- Community Control Mechanisms like CLTs and housing cooperatives that remove land from the speculative market.
- International Cooperation to curb global real estate speculation and support cities in the Global South with grants, not just loans.
- Data Transparency to track where money goes, who benefits, and whether displacement is occurring.