EXAMPLES OF INNOVATIVE HOUSING FINANCE MODELS FROM REALL’S GLOBAL NETWORK IN AFRICA AND ASIA
Introduction
Examples of innovative housing finance models are more critical than ever as over 1.6 billion people worldwide live in inadequate housing. In Africa and Asia, rapid urbanization, population growth, and income inequality have created a massive shortfall in affordable homes. Traditional banking systems often exclude low- and middle-income households due to lack of formal income records, collateral, or credit history. To address this, organizations within Reall’s global network—formerly the Homeless International—have pioneered scalable, inclusive, and sustainable solutions.
Examples of innovative housing finance models from across Africa and Asia demonstrate how creativity, technology, and community engagement can transform access to decent shelter. These models are not just about lending—they are about empowerment, resilience, and long-term development.
Reall’s Role in Advancing Housing Innovation
Reall supports housing entrepreneurs, financial institutions, and policymakers across emerging markets to test and scale new approaches. By providing grants, technical assistance, and impact investment, Reall helps bridge the gap between grassroots innovation and systemic change. Examples of innovative housing finance models supported by Reall include digital lending platforms, incremental housing loans, rent-to-own schemes, and green mortgage products. These initiatives are designed to meet the realities of informal economies and diverse housing needs. Examples of innovative housing finance models show that when tailored to local contexts, financial tools can unlock homeownership for millions.
Digital Credit Platforms in East Africa
One of the most transformative examples of innovative housing finance models comes from East Africa, where mobile technology has revolutionized financial inclusion. In Kenya and Uganda, Reall partners with fintech companies that use alternative data—such as mobile phone usage, utility payments, and rental history—to assess creditworthiness. This allows lenders to offer small, short-term home improvement loans to people traditionally excluded from formal finance.
For instance, in Nairobi’s informal settlements, a homeowner can apply for a digital loan via SMS to repair a leaking roof or install a toilet. Repayment is automated through mobile money platforms like M-Pesa. Examples of innovative housing finance models like these reduce transaction costs, increase speed, and build credit histories over time. They empower residents to upgrade their homes incrementally, improving health and safety without requiring large lump-sum financing.
Incremental Housing Loans in India
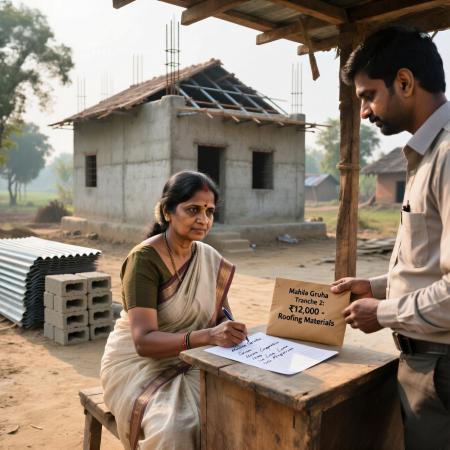
In India, where millions live in self-built homes, examples of innovative housing finance models focus on supporting gradual construction. Reall supports microfinance institutions that offer “incremental housing loans”—disbursed in tranches as construction milestones are achieved. A family might receive the first tranche to lay a foundation, the second for walls, and the third for roofing and sanitation.
This model aligns with how low-income families actually build: slowly, as funds become available. Examples of innovative housing finance models such as this reduce financial risk for both lenders and borrowers. They also ensure that funds are used for intended purposes, verified through field officers or mobile check-ins. By matching loan disbursement to physical progress, these programs improve accountability and construction quality.
Rent-to-Own Schemes in Nigeria
In Lagos, where homeownership remains out of reach for most renters, examples of innovative housing finance models include rent-to-own arrangements. Under this model, tenants pay monthly rent, part of which is saved in an equity account. After a set period—typically five to seven years—the accumulated amount is applied toward the purchase of the home.
Reall supports Nigerian developers and housing finance providers in structuring these schemes with transparent terms and legal protections. Examples of innovative housing finance models like rent-to-own help bridge the gap between renting and owning, particularly for young professionals and informal workers. They also provide developers with steady income while building a future sales pipeline.
Green Housing Microfinance in Bangladesh
Climate change poses a growing threat to housing in flood-prone and coastal regions. In Bangladesh, examples of innovative housing finance models integrate environmental resilience with affordability. Reall partners with local NGOs and microfinance institutions to offer “green home loans” that fund climate-adaptive features such as raised foundations, storm-resistant roofing, and rainwater harvesting systems.
These loans often come with technical training on disaster-resilient construction techniques. Examples of innovative housing finance models in this space show that sustainability and affordability are not mutually exclusive. By reducing long-term repair costs and protecting lives, green housing finance delivers both economic and social returns.
Community-Based Savings Groups in Uganda
In rural areas where formal banking is scarce, examples of innovative housing finance models rely on collective action.
Village savings and loan associations (VSLAs) are community-managed groups where members contribute small weekly amounts to a shared fund. After several months, members can borrow from the pool to finance home improvements.
Reall supports the formalization and scaling of these groups, linking them to larger financial institutions for re-financing or technical support. Examples of innovative housing finance models rooted in community trust are especially effective in areas with low literacy and limited infrastructure. They foster financial literacy, gender inclusion (as many groups are women-led), and social cohesion.
Mortgage Guarantee Schemes in Cambodia
Access to long-term mortgages remains limited in many Asian countries due to high perceived risk. In Cambodia, examples of innovative housing finance models include public-private mortgage guarantee schemes. A third-party guarantor—often supported by donor funding—covers a portion of the loan in case of default, encouraging banks to lend to first-time homebuyers.
These guarantees are targeted at low- and middle-income borrowers who meet certain criteria, such as stable informal income or participation in financial literacy programs. Examples of innovative housing finance models like this de-risk lending while promoting responsible borrowing. Over time, they help build a culture of homeownership and formal credit use.
Affordable Housing Bonds in South Africa
To mobilize large-scale capital, examples of innovative housing finance models in South Africa include the issuance of affordable housing bonds. These bonds are sold to institutional investors—pension funds, insurance companies—and the proceeds are used to finance low-cost housing developments.
Reall works with housing developers and financial regulators to structure these bonds with strong social impact metrics and transparency. Examples of innovative housing finance models using capital markets show how private investment can be aligned with public good. Returns are modest but stable, appealing to socially responsible investors.
Pay-As-You-Build Financing in Rwanda
In Kigali, many families build homes over years, sourcing materials as cash allows. Examples of innovative housing finance models here include “pay-as-you-build” credit lines offered by housing cooperatives. These allow homeowners to draw funds as needed for specific construction phases—foundation, walls, roof—without taking on full debt upfront.
Coupled with technical guidance on quality materials and design, these programs improve safety and durability. Examples of innovative housing finance models that support incremental building recognize the financial reality of low-income households and provide structured support without overburdening them.
Women-Led Housing Cooperatives in Nepal
Gender inequality in property ownership remains a major barrier in many countries. In Nepal, examples of innovative housing finance models focus on women’s economic empowerment. Reall supports women-led housing cooperatives that pool savings and access group loans to build or upgrade homes.
These cooperatives also advocate for land rights and legal registration in women’s names. Examples of innovative housing finance models that center gender equity not only improve housing outcomes but also strengthen household decision-making and resilience. When women control housing assets, entire families benefit.
Technology-Driven Credit Scoring in Indonesia
In Indonesia, where much of the workforce is informal, traditional credit scoring fails to capture financial reliability. Examples of innovative housing finance models use artificial intelligence and machine learning to analyze non-traditional data—mobile transactions, e-commerce activity, and social behavior—to assess credit risk.
Reall partners with fintech startups to pilot these tools for housing microloans. Examples of innovative housing finance models leveraging AI increase inclusion while maintaining low default rates. They represent the future of inclusive finance—data-rich, fast, and accessible.
Leasehold Financing in Ghana
In many African cities, land tenure is a major barrier to financing. In Accra,
examples of innovative housing finance models include leasehold financing, where lenders provide loans based on long-term land leases rather than freehold ownership. This allows tenants on public or community land to access credit for construction.
Reall supports legal reforms and financial product design to make leasehold loans viable and secure. Examples of innovative housing finance models that address land rights expand access to finance without requiring full ownership—a practical solution in complex urban environments.
Mobile-Based Home Improvement Loans in the Philippines
In Metro Manila, where millions live in informal settlements, examples of innovative housing finance models use mobile platforms to deliver small, flexible loans. Borrowers apply via app or USSD code, and funds are disbursed instantly to their e-wallets. Loans are used for critical upgrades like sanitation, fire-resistant materials, or storm windows.
Reall supports local partners in designing user-friendly interfaces and ensuring consumer protection. Examples of innovative housing finance models that leverage mobile technology are fast, scalable, and responsive to urgent needs.
Social Impact Investment Funds in Vietnam
To attract private capital into affordable housing, examples of innovative housing finance models in Vietnam include blended finance vehicles. These funds combine donor grants, concessional loans, and commercial investment to finance developers building low-cost homes.
Reall helps structure these funds with clear impact reporting and risk-sharing mechanisms. Examples of innovative housing finance models that blend public and private capital demonstrate how large-scale change can be financed sustainably.
Rental Financing for Landlords in Kenya
Improving rental housing is another frontier. In Nairobi, most low-income families rent, but landlords often lack funds to maintain or upgrade properties. Examples of innovative housing finance models include rental improvement loans—provided to responsible landlords who commit to keeping rents affordable.
Reall supports pilot programs that link financing to tenant protections and quality standards. Examples of innovative housing finance models targeting the rental sector can improve living conditions at scale, without requiring tenants to become owners.
Cross-Border Learning and Scaling
One of the strengths of Reall’s network is its ability to share examples of innovative housing finance models across regions. A successful digital lending platform in Kenya might inspire a similar model in Pakistan. A cooperative housing scheme in Nepal could inform programs in Ethiopia.
Reall facilitates knowledge exchange, impact measurement, and policy advocacy to help promising models grow. Examples of innovative housing finance models are not isolated experiments—they are part of a global movement toward inclusive urban development.
Challenges and Lessons Learned
Despite progress, examples of innovative housing finance models face challenges. Regulatory barriers, limited financial literacy, and weak land governance can hinder scalability. Some models struggle with high operational costs or low repayment rates.
Reall emphasizes the importance of piloting, learning, and adapting. Examples of innovative housing finance models must be grounded in local realities, not imported solutions. Long-term success requires partnerships, patience, and policy support.
The Path Forward
The future of housing finance lies in innovation, inclusion, and sustainability. Examples of innovative housing finance models from Reall’s network show that scalable solutions exist. From digital credit to green microfinance, these models are transforming lives—one home at a time.
To achieve universal access to decent housing, these innovations must be scaled through supportive policies, investment, and collaboration. Examples of innovative housing finance models prove that with the right tools, even the most marginalized can build safe, secure, and dignified homes.
Conclusion
In conclusion, examples of innovative housing finance models from Africa and Asia offer hope and practical pathways to address the global housing crisis. Whether through mobile loans, rent-to-own schemes, or community savings groups, these initiatives put people at the center of financial design. Reall’s work amplifies these solutions, ensuring they reach those who need them most. As urbanization accelerates, examples of innovative housing finance models will be essential to building inclusive, resilient cities for all.
Also read: Achieving the Sustainable Development Goals Through Affordable Housing in Africa and Asia
