Affordable Housing Investment Strategy
Introduction
Affordable Housing Investment Strategy is no longer a niche concern for social welfare agencies or philanthropic foundations—it has emerged as a compelling, high-impact opportunity for institutional investors, development finance institutions, private developers, and even retail capital seeking stable, long-term returns. As global urban populations surge and housing affordability crises deepen, particularly in emerging economies, the traditional model of relying solely on government subsidies to deliver low-cost homes has proven insufficient.
The new frontier lies in designing an Affordable Housing Investment Strategy that is financially viable, socially responsible, and scalable across diverse markets. This strategy doesn’t ask investors to choose between profit and purpose—it shows how purpose can be the engine of profit.
At its core, an Affordable Housing Investment Strategy is about reimagining housing not as a cost center, but as a resilient asset class. It requires rethinking risk, redefining returns, and rebuilding systems—from land tenure and financing structures to construction methods and tenant engagement.
This summary explores the most effective components of a modern Affordable Housing Investment Strategy, drawing from real-world pilots in Kenya, India, Nigeria, Colombia, and beyond, and distilling them into a practical, actionable framework.
The Urgency: Why This Strategy Can’t Wait
Affordable Housing Investment Strategy begins with a stark reality: over 2.4 billion people worldwide lack access to adequate housing. In sub-Saharan Africa alone, the housing deficit exceeds 30 million units. In India, nearly 70% of urban households spend more than half their income on rent or housing-related costs. In South Africa, informal settlements house over 40% of the urban population. These are not just humanitarian emergencies—they are economic drag factors.
When families spend 60% of their income on shelter, they have little left for education, healthcare, savings, or entrepreneurship. When workers commute three hours daily because housing is too expensive near job centers, productivity declines. When municipalities cannot collect property taxes because homes are informal, public services collapse. The cost of inaction is measured not just in human suffering, but in lost GDP, increased public spending on emergency services, and diminished social cohesion.
An Affordable Housing Investment Strategy is the bridge between this crisis and a sustainable solution. It is not charity. It is capital allocation with intention. It is recognizing that housing is the most fundamental infrastructure—and that investing in it generates returns far beyond the balance sheet.
The Investor’s Misconception: “It’s Too Risky, Too Low Yield”
For decades, the dominant narrative among private investors has been that affordable housing is unattractive. “Low rental yields,” they say. “High default rates.” “Poor maintenance.” “No exit strategy.”
These assumptions are outdated—and dangerously wrong.
An Affordable Housing Investment Strategy challenges these myths with data. In Kenya, SACCO-backed housing projects targeting incomes of R3,000–R7,000 per month have demonstrated repayment rates above 92%. In Colombia, a social housing fund launched by a major pension fund achieved a 7.8% annual return over seven years—higher than the local bond yield—with zero defaults. In Nigeria, a modular housing developer using prefabricated materials reduced construction costs by 35% while maintaining quality, enabling a 9% net operating income.
The real risk isn’t the tenant—it’s the outdated model. Traditional housing finance assumes formal employment, fixed salaries, and bank credit histories. But in emerging markets, the majority of earners are in the informal sector: minibus drivers, domestic workers, street vendors, artisanal miners, and seasonal laborers. Their income is irregular, but it is consistent. An Affordable Housing Investment Strategy doesn’t fight this reality—it designs around it.
Key Pillars of a Modern Affordable Housing Investment Strategy
-
Blended Finance: De-Risking for Private Capital
The cornerstone of any successful Affordable Housing Investment Strategy is blended finance. This means combining public or development capital with private investment to reduce perceived risk and unlock scale.
For example, a municipal government might guarantee 30% of a loan issued to a developer building 500 affordable rental units. This guarantee allows a private impact fund to provide the remaining 70% at below-market interest rates. The developer, in turn, can offer rents 40% lower than market rate while still achieving a 6–8% internal rate of return (IRR).
In South Africa, the National Housing Finance Corporation partnered with the African Development Bank to create a guarantee facility that reduced lender risk by up to 50%. The result? Over 12,000 new affordable units financed in three years, with private capital accounting for 70% of the funding.
Blended finance doesn’t mean subsidizing losses. It means sharing risk so that returns become achievable—and attractive—to mainstream investors. An Affordable Housing Investment Strategy that ignores blended finance is like trying to build a house without a foundation.
-
Modular, Efficient Construction: Lowering the Cost Base
The single biggest barrier to affordable housing is construction cost. In many African cities, building a basic 35-square-meter unit can cost upwards of R300,000. That’s too high for a household earning R5,000 a month.
An Affordable Housing Investment Strategy addresses this through innovation in materials and methods. Prefabricated panels, compressed earth blocks, 3D-printed walls, and locally sourced timber reduce material costs by 25–40%. Standardized, repeatable designs cut labor time and errors.
In Rwanda, a developer using prefabricated steel frames and modular bathrooms built 200 units in 14 weeks—half the time of traditional construction. Costs per unit dropped from R320,000 to R190,000. The developer now operates with a 10% net margin on rentals priced at R2,200/month.
This isn’t about cutting corners. It’s about engineering efficiency. An Affordable Housing Investment Strategy must treat construction not as an art, but as a manufacturing process—with quality control, scalability, and predictability.
-
Tenant-Centric Financing: Rent as Credit
Traditional lenders require proof of employment. An Affordable Housing Investment Strategy rethinks this. It uses behavioral data to assess creditworthiness.
In Kenya, fintech firms now partner with housing providers to track rent payments via mobile money. Tenants who pay consistently for 12 months earn a credit score. That score unlocks access to microloans for small businesses, school fees, or medical care.
This transforms tenants from liabilities into assets. A tenant who pays rent reliably is more likely to pay for utilities, maintain the property, and stay long-term. For investors, this reduces turnover, lowers vacancy rates, and increases cash flow predictability.
One Lagos-based housing operator uses a simple SMS-based system: tenants text “RENT” to confirm payment. The system logs it, sends a receipt, and updates a digital profile. After 18 months, tenants with perfect records receive a “housing equity voucher”—a partial credit toward future home ownership.
This is not philanthropy. It’s financial engineering. An Affordable Housing Investment Strategy that integrates rent-to-credit models sees tenants as long-term partners, not temporary users.
-
Land Access: The Hidden Lever
In most emerging markets, land is the most expensive—and most contested—component of housing. Speculators hold land idle. Title is unclear.
Municipal zoning blocks multi-unit development.
An Affordable Housing Investment Strategy must include a land strategy. This means:
- Securing long-term leases on underutilized public land (e.g., closed schools, disused depots)
- Partnering with community land trusts to acquire land collectively
- Advocating for zoning reforms that allow “missing middle” housing: duplexes, triplexes, courtyard apartments
In Nairobi, a public-private partnership secured 12 hectares of unused municipal land on the city’s western edge. The land was leased to a developer at 1% of market value for 30 years, conditional on delivering 800 affordable rental units. The developer built a mixed-income complex with ground-floor retail, generating additional revenue streams. The municipality now collects property rates from 800 new tax-paying households.
Land is not just a cost—it’s a lever. An Affordable Housing Investment Strategy that ignores land access is doomed to high costs and low scale.
-
Operational Sustainability: The Profit Multiplier
Too many affordable housing projects fail after construction because no one is responsible for maintenance, security, or utility management. Tenants leave. Units deteriorate. Investors lose money.
An Affordable Housing Investment Strategy builds operational sustainability into the business model from day one.
This includes:
- Hiring and training local youth as property technicians (plumbers, electricians, cleaners)
- Creating resident management committees that collect service fees
- Bundling water, electricity, waste, and security into a single monthly fee (R800–R1,200) paid alongside rent
- Using digital platforms to report and track maintenance requests
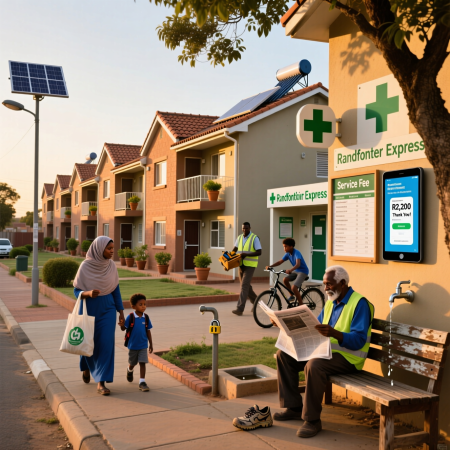
In Klerksdorp, a housing project with 150 units introduced a “Service Fee Model.” Tenants pay R1,000 rent + R600 service fee. The fee funds a full-time security guard, weekly waste collection, solar water heating, and a repair fund. The developer’s net operating income rose from 4.5% to 9.1%.
This is the secret sauce: when tenants pay for services they value, they protect the asset. And when the asset is protected, returns are sustained.
-
Exit Strategies: Making the Investment Liquid
Investors need to know how they’ll get their capital back. For affordable housing, traditional exits—like selling to high-income buyers—are unrealistic.
An Affordable Housing Investment Strategy offers three viable exit pathways:
- Refinancing: Once the asset is stabilized (5–7 years), it can be refinanced by a pension fund or insurance company seeking long-term, low-volatility income.
- Securitization: Rental income streams can be packaged into bonds, sold to institutional investors (as done in Colombia and Mexico).
- Sale to a Social Impact Fund: A second-phase investor can buy the portfolio at a premium, knowing it’s already operational, tenant-proven, and cash-flow positive.
In 2022, a portfolio of 1,200 affordable rental units in Cape Town was acquired by a regional impact fund for 1.8x its original investment value—despite the fact that rents were capped at 40% below market rate. Why? Because the units were well-maintained, had 95% occupancy, and generated consistent cash flow. The buyer didn’t buy bricks—he bought a system.
-
Technology as a Force Multiplier
An Affordable Housing Investment Strategy that ignores technology is leaving money on the table.
Mobile payments reduce default risk. Digital tenant profiles improve credit scoring. Property management software automates billing and maintenance. GIS mapping helps identify optimal locations near transport hubs and job centers.
In Ghana, a housing developer uses a proprietary app that allows tenants to report issues, pay rent, and view their payment history. The app reduces administrative costs by 60% and improves tenant satisfaction by 70%.
Even simple tools—like SMS reminders for rent due dates—have reduced late payments by 40% in pilot projects across Nigeria and Uganda.
Technology doesn’t replace human touch—it enhances it. An Affordable Housing Investment Strategy that leverages digital tools operates more efficiently, scales faster, and attracts younger, tech-savvy investors.
-
Policy and Regulation: The Enabling Environment
No investment strategy can thrive in a hostile regulatory environment.
An Affordable Housing Investment Strategy must include advocacy. This means:
- Pushing for fast-track approvals for affordable housing projects
- Lobbying for tax incentives (e.g., VAT exemptions on building materials)
- Encouraging municipalities to release land for mixed-use, high-density housing
- Supporting reforms that recognize informal housing upgrades as legal assets
In India, the Pradhan Mantri Awas Yojana (PMAY) offers developers a 6% interest subsidy on loans for affordable housing—provided they meet strict affordability and inclusion criteria. The result? Over 12 million units approved since 2015.
Governments are not the enemy—they are the essential co-investor. An Affordable Housing Investment Strategy that engages policymakers as partners, not obstacles, gains momentum.
The Return: Beyond Financial Metrics
An Affordable Housing Investment Strategy delivers returns that extend far beyond IRR and net operating income.
It reduces crime in neighborhoods where housing is secure and well-managed.
It lowers public health costs by reducing TB and respiratory illnesses linked to poor ventilation and overcrowding.
It increases school attendance when children live close to schools.
It empowers women by giving them control over housing decisions and access to collateral.
In one study in KwaZulu-Natal, households that moved from informal settlements to formal affordable rentals saw a 32% increase in children’s school attendance and a 28% drop in hospital visits for respiratory illness. The cost savings to the public health system exceeded the cost of the housing investment.
These are not side effects. They are core outcomes. And they make the investment more resilient, more defensible, and more valuable over time.
The Future: Scaling the Model
The most successful Affordable Housing Investment Strategies are modular, replicable, and system driven.
A pilot in one township can be copied in another with minor adjustments. A digital rent-tracking system can be licensed to other developers. A financing structure using blended capital can be replicated across provinces.
The key is standardization without uniformity. Standardized designs. Standardized financial models. Standardized tenant engagement tools. But locally adapted materials, layouts, and cultural norms.
The goal is not to build 1,000 units. It’s to build a system that can build 100,000.
Conclusion: Profit with Purpose Is the New Normal
Affordable Housing Investment Strategy is no longer a moral imperative—it is a market opportunity. The demand is real. The returns are measurable. The risks are manageable. The models are proven.
Also read: Launch of the Affordable Housing Investment Alliance
