

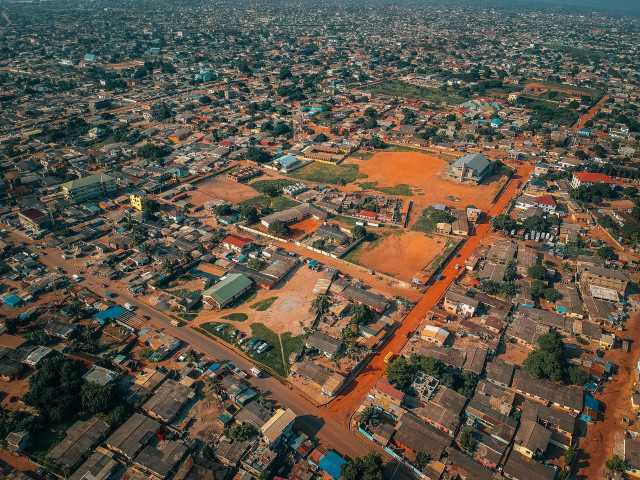
The Case For Affordable Housing Tax Incentives In Ghana: A Policy Perspective
Affordable housing has been one of the most urgent
developmental issues in Ghana up to date. With the ever-increasing population
and the increased pace of urbanization, the housing need has far surpassed the
supply. The growth of major cities like Accra, Kumasi, and Takoradi has
witnessed a tremendous growth in the recent decades where people are flocking
to find jobs, education, and improved lives. Nevertheless, the increase in the
urban population rate against affordable housing units has not been measured,
and as a result, the prices of rent have increased, the population in the city
is overcrowded and informal settlements are expanding.
Housing shortage in Ghana is estimated to be in millions
with the impact being felt mostly by low and middle income earners households.
Lack of affordability of housing options leads to many families squashing a
considerable part of their income on rent or having to resort to informal
housing structures. The very high construction cost, high cost of building
materials, costly access to finance and bureaucratic time wastage in the land
acquisition process have also contributed to the inability of developers to
make housing affordable to common citizens.
Tax incentives as a policy tool to promote the creation of
affordable housing is one of the policies that have been receiving more and
more attention over the past years. The world has had a wide use of tax
incentives to encourage investment in areas that are deemed to be of importance
to the society but may not have enough capital flowing into them through
natural investments. The housing situation is no exception, since through such
incentives, the financial pressure on the developers will be lessened, investors
will be motivated to invest in housing developments that are affordable and
which would eventually lead to an increment in the number of houses that can be
afforded by lower-income earners.
This paper discusses the argument of affordable housing tax
incentives in Ghana as policy-based. It studies the character of the housing
problem in Ghana, the economic justification of tax incentives, the policy
frameworks that may be used, and the overall economic and social benefits that
tax incentives may bring. Through these problems, the discussion indicates how
the tax policy can be a potent instrument in resolving the housing shortage in
Ghana and enhancing living standards of millions of citizens.
Getting to grips with the Housing Crisis in Ghana.
The housing crisis in Ghana is a relatively long-term
problem that has evolved as a result of sharp population increase and
urbanization. The urban population has increased tremendously in the country
with people relocating to the urban areas in search of jobs and better living
conditions. On the one hand, urban development has resulted in the development
of economic opportunities, but on the other hand, it has imposed enormous
burdens on the housing infrastructure and services.
The increase in the disparity between housing supply and
demand has been one of the major causes of the housing crisis. Thousands of new
households are created each year yet the number of new housing units that are
being constructed has not been corresponding to this increase. The high-end
residential development projects tend to attract more attention of developers
as they are more profitable, and developers do not pay much attention to the
affordable housing segment.
Another big challenge is the high cost of construction
materials. Most of the building materials in Ghana are imported and therefore
the developers are subjected to the variability of the world prices and
exchange rates. Raw materials, such as cement, steel, tiles and other basic
needs have over the years become very expensive and it has become hard to be
able to construct affordable houses yet compromise quality.
The housing development is also complicated by land
acquisition processes. The land tenure system in Ghana is a mixture of the
customary ownership and the statutory regulation that may lead to legal
ambiguity and the registration lag. This often occurs as developers have to
face conflicts or extended negotiations with the conservative authorities and
governmental bodies prior to construction.
Besides these problems, many Ghanaians still do not have
access to housing finance. Mortgage interest rates are usually high and down
payments are usually high in financial institutions. This means that a very low
proportion of the population is able to finance mortgage financing and many
households have been compelled to use incremental modes of building
construction which can take years to be finished.
The solution to the housing crisis in Ghana is to hand over
a complex issue that entails changing regulations, financial innovation, and
the encouragement of the involvement of the private sector. One of the possible
instruments that can be employed by the policymakers in order to stimulate more
investment in affordable housing development is tax incentives.
Economic justification of Housing tax incentives.
Tax incentives are best known as an effective policy tool
that can be used to shape the economic behavior and to mold investment to
priority industries. Tax incentives can alleviate the cost to developers and
investors in terms of the financial cost of housing projects since affordable
housing projects are more beneficial as a business consideration.
The development of affordable housing has a low profit
margin in comparison to luxury residential development. The developers have to
strike a balance between construction cost, land-acquiring cost, financing
fees, and regulation cost and ensure that the final selling price is affordable
to low- and middle-income consumers. In the absence of financial incentives,
affordability of housing projects by a number of the developers
This gap can be narrowed with the assistance of tax
incentives as they will reduce the general cost of development. Considering the
example, governments can provide corporate tax breaks or value added tax
waivers on building material or even property tax breaks to developers who
promise to construct low-cost housing units. These incentives will reduce the
operation costs and enable developers to offer the housing units at a
comparatively low price.
In a bigger economic sense, the tax incentives will help to
bring life to the works of construction and create job opportunities. There are
high correlations between housing sector and other sectors like cement
production, steel manufacturing, transportation and financial services. More
funding in housing development will therefore generate employment and economic
growth.
The other economic advantage associated with housing tax
incentives is the possibility that it will bring long term investments by
institutional investors including pension funds and insurance companies. Such
institutions are usually interested in long-term investments that are stable
and affordable housing projects have the potential to offer certain returns
given proper policy frameworks.
Tax incentives might also enhance the solution of finance in
housing by motivating financial institutions to provide mortgage products that
have the potential to suit the lower-income households. Governments can offer
tax incentives to banks which offer low-cost mortgage loans or help finance
housing programs targeting first-time home buyers.
Types of Tax Incentives for Affordable Housing Development
Governments can use a number of forms of tax incentives to
promote the creation of affordable housing. The different kinds of incentives
are used to deal with a variety of areas of the housing development process and
can be customized to achieve certain policy goals.
One of them is the corporate tax relief on the developers
who invest in affordable housing projects. The governments can lower the
corporate income tax rates or provide tax incentives to the developers who set
a specified portion of their development to affordable housing units. This
makes developers incorporate cheap units in the bigger residential development.
The other incentive that is popular is the waiver or a
discount on the value-added tax (VAT) on construction materials to be used in
the production of affordable housing. Building materials are a major part of
the construction expenses, and a cut in the VAT cost imposed on building
materials can help cut the total cost of developing houses by a significant
percentage.
Incentives in the form of property taxes may also be
significant. Governments can provide temporary exemptions in property tax on
newly built affordable housing units or lower property tax rates on developers
and homeowners of the affordable housing programs. Such measures ensure the
housing projects become more economically feasible.
Besides the developer incentives, tax break can be given to
those investors who fund affordable housing programs. Some examples are
governments permitting investors to deduct some investments in housing to their
taxable income or providing tax credits on investments in housing funds.
With these various forms of tax incentives, the policymakers
are able to develop a holistic approach that can be used to assist developers,
investors and homebuyers concurrently. Such a combined strategy raises the
chances of having significant improvements in the provision of affordable
housing.
Encouraging Private Sector Participation through Tax Policy
The role of the private sector in housing development is a
very important aspect especially in countries that have limited resources by
the government. In Ghana, the high earnings residential projects have been the
focus of the private developers in the past because it has a better profit
margin. Nevertheless, developers can be convinced to invest more significantly
in affordable housing with the help of specific tax incentives.
Tax policy has the potential to affect the investment choice
due to the change in the financial risks and rewards of the type of the
project. The profitability of such projects becomes possible when the
developers are given tax provisions on building low-cost housing units. This
can encourage the companies to focus more on inclusive housing developments.
The introduction of tax credits which are directly related
to the amount of affordable housing units built is one of the effective
strategies. The builders that construct cheaper housing will get higher tax
incentives and this will be a direct stimulus to increase the supply. Such
programs have been tested successfully in various countries and have been very
effective in building more affordable houses.
Alliances between government agencies and private developers
can also be stimulated with the help of tax incentives. The governments might
offer land or infrastructure in these partnerships with the developers
contributing construction skills and funding. Tax exemptions are one way of
making sure that such partnerships are economically viable to the partners who
are privately owned.
The other means by which the tax policy can motivate the
involvement of the private sector is by cutting regulatory expenditures
incurred in the development of houses. There are many fees, permits, and taxes
that developers are expected to incur during the construction process.
Development can be more attractive through the streamlining of these costs and
specific exemptions about affordable housing development.
Banking organizations are also relevant to the development of housing. Mortgage lenders and other banks can be motivated by tax incentives to provide funding products that suit low cost housing development. This assists developers to raise funds and makes homebuyers to acquire mortgages at better terms.

International Housing Tax Incentive Programs.
A lot of nations worldwide have managed to execute tax
shelter initiatives to encourage the creation of affordable houses. These
programs also provide good lessons that Ghana can take into consideration in
developing its own housing policy framework.
An example of one of these is the Low-Income Housing Tax
credit program in the United States. According to this program, investors who
fund affordable housing initiatives are given tax credits. The credits decrease
the tax expenses of investors in terms of a few years, which makes the
affordable investments on housing very financial. Since its launch, the program
has been used to fund millions of affordable units of housing.
The United Kingdom has government policies which come in the
form of tax breaks on developers involved in programs of affordable housing as
part of larger residential developments. Planning regulations that could
require developers to set aside some of the new housing development to
affordable units tend to go hand in hand with these incentives.
Other countries, including Singapore, have implemented
extensive housing policies that have been a combination of tax breaks and high
government intervention into land development and housing finance. Such
policies have helped Singapore to record one of the best homeownership rates in
the world.
Tax incentives have been applied in South Africa to promote
the development of rental housing to the low- and middle-income households.
Such incentives are accelerated depreciation allowances on residential building
where developers can recover costs of construction in a shorter period of time.
Certainly, these foreign experiences prove that tax
incentives may be a useful instrument when incorporated in a more overall
housing policy. Effective initiatives are usually a mix of monetary rewards and
regulation reforms, infrastructural investment, and robust institutional
control.
Possible Obstacles to the Housing Tax Incentives.
Although the housing tax incentives are associated with
numerous benefits, there are also several challenges associated with their
implementation that should be taken into account by the policymakers. Tax
incentive programs might not realise the desired goals when designed and
managed improperly or can result in other economic distortions.
The threat of the losses of revenues to the government is
one of the possible challenges. Tax incentives lower government taxes within
the short term that may influence the finances of the people in case such is
not handled effectively. The policy makers should therefore make sure that the
economic gains of greater housing development in the long run are more than the
short term loss in tax revenues.
The other hurdle is to make sure that tax breaks will lead
to affordable housing construction, but not the enhancement of profits of
developers. Devoid of guidelines and monitoring systems, developers are likely
to claim their tax benefits without having to produce housing units that are
truly affordable by lower-income families.
The problem can also be an administrative complexity. The
problem is that implementing the tax incentive programs needs good coordination
among tax authorities, housing agencies and local governments. The
institutional capacity can be weak resulting in delays, mismanagement or misuse
of incentive schemes.
Also, it may be the case that larger developers who have
more financial means and administrative ability will receive more benefits
because of tax incentives. Smaller developers and community-based housing
programs might be unable to utilize these incentives in case the procedure of
the applications is not complex enough.
Conclusion
Housing deficit in Ghana is one of the most crucial issues
of the development of the country and its urban life. The high rate of
population increase, the escalating cost of building, scarce housing finance
facilities, and the cumbersome land administration systems have led to the
continued inadequacy of affordable units of dwelling. To overcome this problem,
new policy solutions should be applied that would stimulate investment and help
to make sure that housing will be affordable to the households of lower and
middle-income.
One potential policy instrument that can be used to achieve
these goals is tax incentives. Tax incentives will encourage the creation of
affordable housing and increase access to homeownership by making it more
affordable to developers, investors, and homebuyers. These incentives can allow
the private sector to serve the interests of the public policy when properly
formulated and incorporated into a wider housing policy framework.
Tax incentives should however be introduced with a keen
sense of governance, transparency as well as long term sustainability. The
policymakers should make sure that incentives will provide real housing results
and not just a cut in taxation payments to the developers. The effectiveness of
housing incentive programs will require strong monitoring systems, transparent
eligibility requirements, and frequent assessment of policies to ensure the
effectiveness of these programs.
-3dkuLgKhRD.jpg)
-49HupTvwDD.jpg)
LEAVE A REPLY