

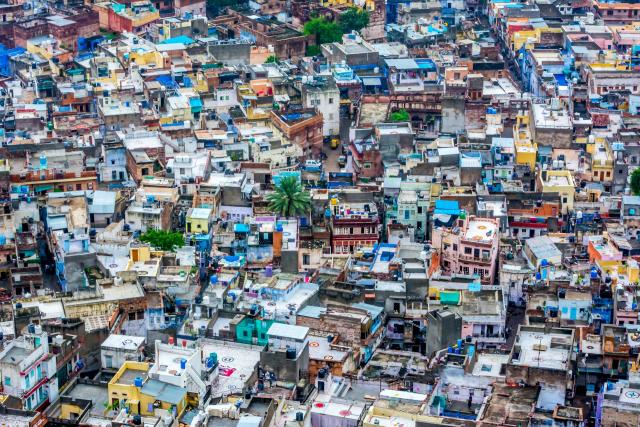
SVAMITVA Success Story: How Rural Land Titles Are Fueling Affordable Housing Loans
Millions of households in rural India have long been settling in non-documented houses, turning the biggest asset of their households, land, into dead capital. These families are excluded in access to credit, land use and civic planning without legal titles. SVAMITVA ( Survey of Villages and Mapping with Improvised Technology in Village Areas ) was launched in April 2020 to fill this gap with a drone survey and issue of Property Card with the backing of GIS incorporation in 3.17 lakh villages and 2.25 crore cards issued to date.
The scheme has been stretched to March 2026 with the aim of sweeping all the 6.6 lakh villages. In addition to mapping alone, SVAMITVA gives the homeowner in rural areas the ability to pledge the land, opening the doors to access affordable housing, entrepreneurship, and even more local areas can plan with government revenue. We will unfold the institutionalization process of SVAMITVA, any financial connectivity, its social impact, housing context, institutional links, challenges, and prospect in this blog.
Technological integration, and Institutional Scale-up
SVAMITVA has recorded one of the rapid institutional implementations in the history of governance in rural India. Since its pilot in eight states in 2020, it has reached over 3.17 lakh villages (more than 90 percent of the intended rollout), and has issued more than 2.4 crore property cards. Drone mapping, which is supported by the GIS layers and checked using the local verification standards, allow gram panchayats and the revenue authorities to undertake the ground truth of land surveys at scale, which was long in a rural agglomeration that has been usually part of the traditional governance arrangement, but not the digital governance system.
The integration of data with such platforms as Digital India Land Records Modernization Program (DILRMP) and GramSwaraj makes land records updatable and available. Transparency in land titling has become extremely high in mapping and QR coded property cards, limiting delays in time and boundary disputes. Nevertheless, here are areas of concern in tribal regions where there is a PESA law and exceptions on a state-to-state basis as in the case of Tamil Nadu, Bihar and West Bengal. However, the fact that state and national stakeholders like the world governance forums such as the World Bank Land Conference have adopted SVAMITVA suggests a paradigm shift that it is destined to
Access to Institutional Credit
The relevance of the conversion of the undocumented land to the titled asset has opened a flood of bankable collateral. Verified households can now obtain housing loans, credit to run businesses and many others since the rural households are validly requesting credit. An example here is the Tashi Gailson of Leh, who having had a new property in his name, got 15 lakh rupees to turn his family home into a homestay. The technical groundwork of the scheme, exact maps, survey-worthy ownership verification, and in digital formats, has also generated activity among government-owned banks and the non-banking finance companies, where a growing number of lenders are ready to underwrite home loans in the rural area.
Nevertheless, movement is still being made in other states such as Maharashtra, UP, MP, Punjab and Gujarat even though legal restriction continues in states such as Uttar Pradesh where mutations not yet been permitted to be made on residential property. In property-backed loans, the beneficiaries are unfolding in improvement of their houses and fitting of clean-energy and small businesses-this is one testimony on how SVAMITVA is turning idle land into economic opportunities.
Financing Inexpensive and Gradual Rural Housing
The effect of SVAMITVA on rural housing can be among the most crucial byproducts of this project. Now armed with title deeds, even humble country estates now become securable to a bank. As per the print, homes surveyed under SVAMITVA have helped proprietors to get finances to enlarge or revamp their abodes unlocking formal housing financing facility on low-priced houses in the country areas. The figures indicate that the number of beneficiaries taking up a small loan under PMAY-Gramin and state credit-linked subsidy schemes has been increasing to improve the housing.
This allows rough improvements being made gradually, adding rooms, banning the kutcha (not-so-good) walls to become pukka walls, installing sanitation, or solar panels, all that improves the quality of rural housing. Practically, SVAMITVA sows the seed of a bottom up scaling up with rural stock to far beyond what is first mapped.
Women Rights, Social Justice, and Dispute resolution
SVAMITVA property titling is not just economic, it is also a social boost in terms of equity and gender inclusion. Under this scheme, joint titling is promoted and women can be recognized as co-owner. The empowerment through such legal acknowledgment is very important as it allows women to exercise their rights to an inheritance and collaterals. Property card has gained headline as a paradigm shifting instrument of Dalit and backward-class families.
Formalization of property ownership also lowers disputes over land-this is a significant intended consequence of SVAMITVA which was recognised by the government. There has also been easy tracing of land and this has made people pay their property taxes, also, it helped the gram panchayat make better plans and it also made rural governance transparent.
Partnerships and Long-Term Integration of Institutions
SVAMITVA is a success-story of multi-stakeholders. The institution level of operation is between the Central Government (Panchayati Raj Ministry), Survey of India and State revenue Departments with institutional structure of adjudication over claims (between the parties). Field verification is helped by NGOs and local panchayats particularly in community outreach programs and literacy programs. Deployment of drones, GIS mapping and back-end integration are supported by technology partners.
In addition, the fact that at the start of 2025 the PM had distributed 65 lakh property cards showed a high level of political buy-in, with MMNRs by the Prime Minister highlighting property cards as the points of origin of economic empowerment. In the future, the scheme is intended to utilize digital land records to facilitate more complex uses, such as geospatial planning, decentralized property tax systems, and (potentially) pilots of block chain-architected land registration schemes in a handful of states.

Implementation Challenges & Systemic Limitations
Nonetheless, although it is sweeping in scale, SVAMITVA has some obstacles. Close to 30 % of the villages (particularly in tribal, Northeast and PESA states) have not been recorded yet out of legal or cultural tangles. The problem of post-surgery mutations remains alive in the states where the residential land is yet to be mutative- such as UP. Mappings are also not possible due to drone limitations in sensitive ecosystems or even the borders.
On the one hand, digital literacy disparities go against the employability of property cards among the beneficiaries. In addition to that, cash-strapped households can seek credit even without comprehending the terms of the loan, despite their better tenure. Nonetheless, several of these concerns are being worked upon actively through state-based reforms and the modernisation of back-offices, where currently, it has been found that tribal states such as Mizoram are making noticeable progress in the introduction of the program.
Future Roadmap: Affordability Housing and Scalability
The future of SVAMITVA is in the integration of land titles into the formal housing finance. It is planned that property cards will be linked to PMAY-G investments, thus the rural house owner will be eligible to get subsidy benefits and formal mortgages on the basis of his/her titled plot. It has been estimated that there may be 100100 lakh crore of rural capital unlocked and this is a huge source of credit to house, enterprise and local economy.
By converting titled land into low-cost housing finance programs with technical support on the planning of infrastructure an SVAMITVA may not only empower rural households, but also legalize rural villages themselves. The institutional credit together with the legal power of titled property are likely to bring a massive boost up to the quality of housing in rural countries.
Land to Loan: How Digitized Titles Are Reshaping Rural Creditworthiness
Rural economy in India is something that has never been a part of formal finance. Although agriculture and related activities form the heart of rural livelihoods, majority of the inhabitants of the rural home could not access structured credit since they had not the basic financial document; proof of land ownership. The conventional banking instruments were based on collateral which in the rural setting usually was land. .
However, millions of rural families resided on ancestral land or slums that were not documented, leaving a gap in credit along with exposing the citizens to unfriendly informal lending habits. It has started to change with the advent of government supported titling programs such as SVAMITVA, and state level cadastral reform. These reforms are converting land resources that had remained hidden assets to a bankable resource by making property records digitally, legally and geo-referenced.
This situation is changing, with lending institutions beginning to accept the SVAMITVA property cards as collateral on personal, home improvement or micro enterprise loans, public sector banks, co-operative banks, and MFIs are doing in this regard. Interestingly, fintech lenders are also incorporating property title checks to their risk assessment model, which is simply allowing rural residents to obtain loans at lower interest rates and bigger repayment plans than ever before, as was the case with informal lenders. In addition to the people, such digitization is also enabling panchayats to realize the potential of data with regard to raising revenues, plan infrastructure according to the availability of credit, and financing according to the progress on the development.
It is also advantageous to the banks: as in the case of default risks, formal ownership and correct valuation of underlying asset are the way out. In addition, GIS-based titling simplifies the foreclosure procedure in worst-case situation which increases lender trust.
This shift has practically enabled numerous households to achieve financial freedom by coming out of the poverty-debt circle. Indicatively, in the Dang region of Gujarat the newly printed property cards enabled small borrowers to obtain formal financing of poultry sheds, solar pumps, or pakka home extensions- creating both tangible and financial assets. Nevertheless, it is not a smooth ride.
The latter feature of financial literacy is uneven and representatives of many residents do not entirely comprehend the terms of loans and the cancellation of obligations. Capacity building of lenders is also necessary: the staff in rural branches of banks is not always aware of the SVAMITVA-related property and is reluctant to provide loans. To achieve a real change, it will be necessary that financial institutions streamline the process of incorporating digitized titles into appraisal and documentation of the titles with the aid of rural loan counselors.
States are supposed to see to legal enforceability of these records by virtue of updating mutation and integrating state level revenue systems. When it is done properly, this reform will not only open the rural credit, it will make rural Indians not only the second-class citizens of the credit economy, they will become the top priority citizens of the credit economy. Land-property is not primarily a place to stay or cultivate, anymore but a basis of mobility in the credit market. It is the road leading to the transition of land to the loan which will determine the rural credit structure of India in the future.
Shelter to Security: Formal titles and changing the rights of women to housing
Women in India used to be denied equal rights to property in spite of the fact that they were at the core of home management, agriculture and making decisions in the household in rural India. Women have an insecure and invisible housing rights since their names had never appeared on land records because of inheritance laws, social conventions and patriarchal systems.
The SVAMITVA scheme and other such initiatives, however, have brought in a fourth avenue to the empowerment of women by leveraging the aspects of having a property title ownership experience jointly between wives and husbands. This is a mere change of administration on the part of the government but the results are far reaching. Women with names on official property cards now have legal interests in family land, house and house improvements.
This raises their bargaining power in the household level, provides them with safety, should they be abandoned or widowed, and most importantly enable them to secure credit in their names. Home loans have also now been offered by banks and NBFCs with women as co-borrowers at special rates thus making it even more beneficial to include them in these lending activities. A lot of housing subsidy programs, including PMAY-Gramin and PMAY-Urban, now require or promote women ownership to receive the subsidy.
These joint names in titles are gradually becoming the order of the day in the new documentations under SVAMITVA. It can be seen in the anecdotal accounts of Madhya Pradesh, Rajasthan and Maharashtra. Females who used to be afraid of being evicted or have no control over the house upgrading now request house upgrades without fear of being turned away or apply microloans based on their share in titled land.
In Dahod region of Gujarat, women self-help groups have gone to the extent of lobbying with local panchayats to make women titling clearer through the support of civil society organizations. This goes beyond representation: during crises, situations do occur like when the individual is widowed, divorced or when land dispute arise, these official titles get the person anchored in the law with vulnerability being curbed. However there are still struggle. In most of the villages, there is still social opposition to placing the names of women on property.
Surveyors or panchayat officials lose track of implementation when female inclusion fails to draw the attention of the surveyors or the name of the male head is entered automatically. Women still have a low level of legal awareness and most of them do not know their rights concerning the established property laws. Law and legal literacy awareness textual measures and outreach efforts are necessary to close this data gap between men and women.
The presence of the judiciary is also important in this as without quick enforcement of women in their rights to property as laid out in the protection laws, inheritance laws etc., enforcement of change in administration will fail. What is happening, nevertheless, is a paradigm shift: the land ceased to be a male property only, but a family property. Women were first free of rights on housing but now it is ingrained in the system of governance itself. With the formal titles, women in rural India not just get secure shelter, but protection, face, and claim of their own destiny. And this transition is the real triumph of the provisions of inclusive housing.
Conclusion
SVAMITVA has proven that legal-event supported land tenuring in digital form can completely transform the socio-economic direction of the rural India. The scheme has opened up the possibility of housing loans, guaranteed the rights of women, solved inter-communal conflict, enhanced revenues and triggered kick start rural housing, all this being born out of drone mapping, transparent titling, and targeted institutional coordinating.
Its complete transformative power, however, lies in the elimination of the existing implementation gaps-- particularly in tribal areas, PESA regions and digital literacy. Should SVAMITVA reach national coverage in 2026 as hoped, and legitimately transform titled property into collateralized dwelling, then the project will have redefined the path of rural housing in India. The SVAMITVA initiative is more of a tool of empowering rural communities, financial inclusion and providing decent shelter and less of a land-recording exercise, which is a true gamechanger to the inclusive home ownership in the country.
Alos Read: A Housing Loan Guarantee for the Informally Employed
LEAVE A REPLY