

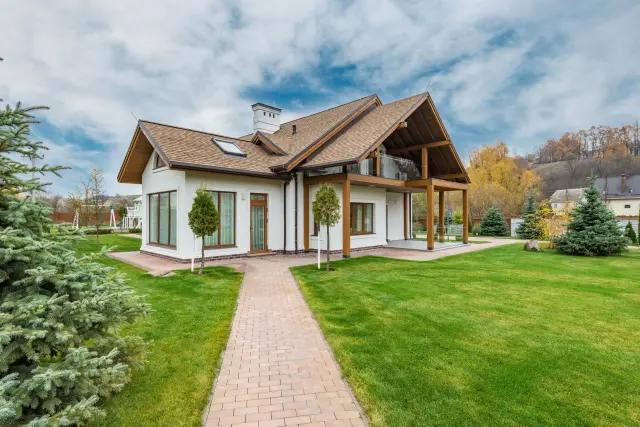
Starter Homes” Policy: How to Define, Size, And Finance Them
Starter homes have become very popular topics in policymaking, although they are usually loosely characterized. In certain situations, they are regarded as mere miniatures of traditional housing, whereas in other situations, they are synonymous with low-income or subsidized housing.
 This confusion results in the use of inconsistent standards, unrealistic promises of affordability, and designs that would not support the needs of the household in the long run. Otherwise, the problem with starter homes is that they can become too small to be decent or too costly to be affordable.
This blog discusses the concept of starter homes as a strategic housing policy tool and not a catchphrase. It addresses three interdependent questions, namely, how starter homes should be defined, how big they should be to work effectively, and how they can be financed in a sustainable way.
The discussion focuses on long-term affordability, gradual development and its correspondence with household life cycles. The following content discusses the policy rationale, design concepts, size factors, land and planning systems, financing concepts, as well as long-term effects of starter homes.
The two offer together a viable basis to governments, planners, developers, and housing advocates who may want to make starter homes a viable and sustainable part of inclusive housing systems.
Our definition of Starter Homes as a Policy Category
The key to an effective starter homes policy is a clear definition of it that is functional. Starter homes must not be described and determined by their size or price, but rather by their place in a greater housing trajectory.
Fundamentally, starter homes are low-level residential houses meant to house families able to afford something in terms of home but not fit in the mainstream housing market. They are supposed to be cheap initially but can be upgraded, expanded or changed with time.
Starter homes are not primarily concerned with the provision of shelter as is the case with emergency or social housing. They are concerned with permitting asset accumulation and formal tenure of households at an early stage in the economic life cycle.
This difference is significant as it forms design criteria, funding anticipations, as well as target the beneficiaries. Starter houses must be simple yet stable, legally acceptable and linked to urban infrastructure and job market.
The definition of policies should clearly differentiate between starter homes and minimum housing. The initial housing should be able to be basic in terms of safety, health, and dignity.
Finishes and room numbers can be reduced, but the structural stability, sanitation, and availability of services cannot be postponed. The stigma associated with starter homes being incomplete or provisional usually results in the construction of low-quality houses and social costs in the long term.
Another important part of the definition is eligibility. The policy of starter homes should focus on first-time buyers in a specific income bracket that is not taken by higher-income earners or the speculators.
Local resale and rental prohibitions in the early years can achieve cost-effectiveness and provide a way to make sure that public assistance benefits are received by households.
Diversity is also strongly defined. Starter homes can be of varied forms according to contexts, which can be apartments, row houses or detached units. What they have in common is a common policy agenda: to reduce the barrier to access to safe, formal housing without trapping households in substandard living conditions.
Sizing Starter Homes for Livability and Growth
The most contentious element in terms of policy design is the establishment of the correct size of the starter homes. The pressures to save costs usually drive to too-small units to meet the household demand, which causes overcrowding, improvised extensions, or total abandonment.
Meanwhile, large units negatively affect the affordability and the amount of served households. Good sizing will combine the affordability in the short-term and the endurance in the long-term.
Starter homes are supposed to be sized according to the real way of life of households and not necessarily by the abstract minimum requirements. Basic functional areas are required even to a small household, consisting of a safe sleeping space, a multi-functional living area, a kitchen or a cooking space and a sanitation area. Very small units that do away with these differences can cut down the cost of construction but tend to fail in the social and cultural aspects.
Planning on how to grow is also important. Most starter home families are young and anticipate that family size, income, and livelihood will change as time passes. Houses with no possibility to be extended either vertically or horizontally cause households to resort to informal adjustments, which undermine the quality of the neighborhood and safety.
Not only should the minimum initial size be defined by policies, but the maximum possible expansion and clear incremental development should also be fixed.
The size of the plot and the size of the building are just as important as the area. Phased construction plots, which tend to be slightly larger, have better long-term results compared to fully built micro-units that do not have the ability to accommodate. Structural systems in multi-family developments must be created to support further internal reconfiguration.
Notably, the standards of sizing must be context-oriented. What is thought to be habitable in one cultural or climatic environment may not suffice in another. Data that has been gathered locally, post-occupancy research, and community consultations ought to inform policy makers about the need to establish sizes that promote dignity and stability as opposed to just meeting minimum standards.
Planning Frameworks, Land and Location
The land policy is a decisive factor on whether starter homes are affordable or not. In most cities, land prices constitute majority of the housing prices and thus it is not possible to provide affordable units without a conscious intervention of the government. Starter homes policy thus has to be closely associated with land acquisition, zoning as well as planning systems.
Location is critical. New homes located on the outskirts of large cities might cost less at the start but create high expenditures in the long term to households due to transportation, lost earnings, and inaccessibility of services.
Starter homes need to be in well-located land close to employment and infrastructure to help in economic mobility. Major tools in achieving such locations include public land, land readjustment schemes as well as inclusionary zoning.
The planning regulations usually provide an indication of the feasibility of the starter homes. Small, affordable units may have become illegal by default as a result of minimum plot sizes, parking regulations, and low-density zoning standards.
Direct subsidies are oftentimes less effective than the reform of these regulations. Several issues such as higher densities, mixed-use development, and incremental construction, will help the market to create starter homes more effectively.
Provision of infrastructure should be planned with the provision of housing. Starter homes that lack a decent supply of water, sanitation, power, and access roads soon go out of value and do not sustain life. Slow infrastructure development in proportion to slower housing expansion can lower initial expenses but provide coverage of services in the long run.
Good planning structures do not consider starter homes as subsidiary or transitional measures in the city. Incorporating them into regular city planning routines assists in rendering the affordability-oriented housing normal and avoids the geographic segregation of low- and middle-income households.
How to Finance Starter Homes with First-Time Buyers
The most significant obstacle to the accessibility of starter homes is often financing to eligibility households. Conventional mortgage products are still not available to many first-time buyers even with the lower unit prices, because of income fluctuations, absence of credit history, or large down payment requirements. The policy of starter homes should thus cater to both supply-side and demand-side financing limits.
In the supply side, the cost of development needs to be reduced. This can be done by offering land to the people publicly, subsidizing infrastructure, tax breaks, and easing the procedures of approval. The reduction of these costs enables the developers to offer units that are affordable to target households without necessarily compromising quality.
Tailored financial products come in when it comes to demand side. The gap between market prices and household capacity can be filled by incremental mortgages, rent-to-own arrangements, shared equity schemes and housing savings programs. These tools appreciate that affordability is a dynamic concept and it increases with the increase in incomes.
The public support must be planned in such a way that it will not distort the market. Instead of huge initial subsidies, the policies could be aimed at making lenders less at risk, either by partial guarantees or subsidized interest rates. This introduces the starter home market to private finance and restricts the long term financial exposure.
Also important are financial literacy and consumer protection. New customers are especially susceptible to predatory lending, or unrealistic payments. Price openness, contract clarity and educating buyers make the starter homes more likely to be affordable and sustainable to households in the long term.
Long-term affordability, equity and policy outcomes
It is not the quantity of units developed, but the end results that a starter homes policy can achieve in the long run. Houses which are affordable at the time of purchase but not affordable to live in, maintain or renovate do not fulfill their policy goals. This should be long-term affordability first of all.
Resale and speculation is one of the issues. In the absence of restrictions, the starter homes may not only be snatched into the open market within a short period, certainly not to the future households.
These can be time-lapsed resale limitations, shared equity opportunities or price limits based on income increase to maintain affordability, though enabling households to accumulate wealth.
Maintenance and management also have an impact. The faulty developments crumble and worsen the quality of life and assets. Policies are supposed to stimulate homeowner associations, cooperative management, or municipal support structures which are shared spaces and infrastructure.
Consideration of equity is not limited to income. The policy of starter homes must cover the gender, age, and diversity of households so that the women-headed households, young families, and informal workers can also be able to access it. The use of clear allocation, as well as non-discriminatory design norms, contribute to fairness and acceptance in society.
Starter homes policies may help to create more inclusive cities, balance sheets within households, and less strain on informal housing markets when properly designed. They will easily turn into a temporary low cost experiment when they are designed poorly.
The precise definition, measurement, and funding are not technicalities, however, but key policy success factors.
Implementation Challenges, Trade-Offs, and Common Policy Mistakes
Policies on starter homes which are well designed usually fail in implementation. It is the disjuncture between intention and policy manifestations that has caused most starter home programs have lost their credibility. Being aware of typical challenges and trade-offs is useful in enabling policymakers to avoid the same mistakes that lead to poor quality, affordability, and mistrust.
Another common problem is that of political pressure to achieve visible outcomes in the short term. This tends to cause excessive construction ambitions, expedited approvals, and cost or place choices.
Starter homes constructed either far away work or without sufficient services can satisfy a numeric quota but fail homes in reality. There should not be short-term measures of delivery that supersede long-term livability and economic viability.
The other one is over dependence on fixed price caps without mitigating underlying cost drivers. Price caps distort developers towards downsizing or declining quality rather than efficiency in land prices, infrastructure charges and regulatory costs that are high.
This ends up in houses that are technically a starter unit but fail to suit the household requirements. The policy should be effective in terms of reducing structural costs, rather than merely managing the final prices.
Risks are also presented by the eligibility and allocation systems. Weak verification enables higher income households or investors to reap advantages whereas too strict criteria lock out informal workers or those households with varying incomes. Starter homes policies should find a balance between being very precise and including everyone, aware of the realities of labor market in most urban areas.
Lastly, a lack of focus on post-occupancy results will decrease the success in the long term. Policies do not adapt or get better without tracking the way households use and extend and sustain their homes. Informal extensions, patterns of resale and household mobility are good feedbacks, which are not paid attention to.
The recognition of the challenges does not undermine the argument of starter homes. Rather, it enhances policy-making through grounding ambition on evidence. Starter homes are not only successful by the idealized models but by constant learning, adaptation and sincere evaluation of trade-offs.
Conclusion
Starter homes can be best seen as a strategic entry to a housing system, as opposed to an affordability act. Clear definitions assist in focusing on the correct families, correct sizing will allow a livable room, and considerate financing systems will reduce the gap between the dream and the reality. Collectively, these factors will make starter homes a feasible political slogan and a lasting solution to housing problems.
The policymaker dilemma is to be ambitious but not exist in the clouds. Starter homes should be neither too cheap nor too poor, neither too loose nor too informal and encouraged without bending the markets. To balance this, there should be alignment in the areas of housing, land, planning, and finance.
The escalating cost of housing is rendering safe and decent housing unattainable to millions of households and the necessity to find real and inclusive solutions is becoming more pressing.
In this regard, the starter homes are a plausible option to households that cannot access the traditional homes market but can build the assets slowly. Starter homes can offer secure tenure, stability and a base on which future economic betterment can be established by reducing the barrier to entry into formal housing.
Well defined, and properly sized starter homes with well thought-out financing and planning programs can allow households to enter into the housing system without being stuck in poor living arrangements. They are not merely cheap at the outset, but can be used with modification as the households grow and their incomes fluctuate.
Based on evidence and operating over the long term, starter homes have the potential to be central to the creation of more resilient, equitable, and inclusive housing systems that can effectively address the increasing affordability pressures.
Also read: The Role Of Technology In Solving Ghana’s Housing Crisis: Smart Homes And Innovative Solutions
-bsBmIgEW58.jpg)
-5yCS4OoVBg.jpg)
LEAVE A REPLY