

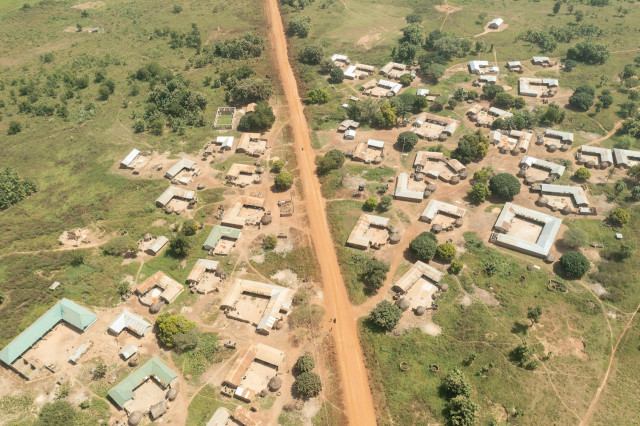
The National Homeownership Fund: A Game-Changer For First-Time Homebuyers In Ghana
Homeownership is one of the most important milestones of the
persons and families in Ghana. However, the dream of owning a house has been
far-fetched to many first time buyers since property prices are very high,
long-term access to mortgage financing is restricted, and down payment is high.
Demand has also risen due to rapid urbanization in cities like Accra and
Kumashi that has increased the cost of land and building. Although the
government housing projects and the privates have tried to bridge the housing
disparity, the affordability aspect remains a problem with young professionals
and low-to middle-income earners being the most affected.
To address these issues, a radical policy proposal has come
up to make homeownership more affordable to first-time buyers in the form of
the National Homeownership Fund (NHF). The fund will aim at offering funding
schemes that lower the entry barriers especially the cost of initial payments
and high-interest mortgage. The NHF aims at making the housing market more
inclusive by mobilizing both public and private capital, and aligning with
other housing and financial sector reforms.
This blog discusses the functionality of the National
Homeownership Fund, its strategic goals, funding process, and eligibility, the
economic relevance of the program, the opportunities, and the risks of
implementation of this program. As Ghana moves toward sustainable urbanization,
the NHF might be an inflection point in the increase of homeownership and the
further reinforcement of economic stability.
What caused the Housing Affordability Crisis in Ghana?
The housing market of Ghana is going through a structural
and economic-induced affordability crisis. High population growth, the rise in
migration of people to urban areas, and escalating construction prices have
left a shortage in housing in the hundreds of thousands of units. The prices of
residential houses have been rising a notch higher in cities especially in
Accra making formal housing unaffordable to most working households.
The cost of land acquisition and provision of the
infrastructure is among the major challenges. The developers are forced to buy
the land at the market value; they have to pay the utilities and road access
and build the construction using high-interest loans. These expenses end up
being transferred to consumers. In the case of first-time homebuyers, this is
further exacerbated by the fact that long-term mortgage financing is not easily
available to them. The short- to medium-term loans that are often provided by
commercial banks are usually charged quite high interest rates, and thus,
monthly payments cannot be afforded by most.
Moreover, the down payments are usually between 20 and 30
percent of the property value. To a humble house this can be years of savings.
The household purchasing power is also pressured by inflationary pressures and
currency volatility. This has led to several families staying in rented or
informal settlements, putting off or giving up on owning homes.
There are also more socio-economic impacts of the housing
affordability crisis. This restricted access to safe housing has an impact on
wealth accumulation, social mobility and the general quality of life. The
market alone just finds it difficult to provide affordable options on a scale
without specifically targeted financial interventions. The National
Homeownership Fund aims to counter the effect of these systemic obstacles by
reducing financial requirements and developing systemic support to first-time buyers.
Objectives and Strategic Vision of the National Homeownership Fund
The National Homeownership Fund has a definite strategic
plan which is to increase access of affordable homeownership to first-time
buyers in addition to maintaining stability in the housing finance market. Its
major aim is to lessen the financial burden that cannot enable the qualified
persons to own homes. The fund will open the demand and drive up supply by
addressing the greatest barriers, namely down payments and high financing
rates.
One of the aims of the NHF is inclusiveness. The campaign
targets low and middle-income earners, especially the young professionals who
have steady jobs but have little savings. With this population being supported,
the fund bridges a serious gap in the housing market in Ghana. It is also in
line with the national development goals, which are aimed at creating wealth
and social equity.
The other strategic objective is to use public funds in
order to crowd in the private capital. The NHF is not a complete subsidizer of
housing, instead it is a catalytic instrument. State support builds confidence
among the lenders and developers to be part of affordable housing programs.
This combination strategy is scalable and sustainable.
The fund also aims at harmonizing homebuyer support
mechanisms. It minimizes the element of uncertainty and builds trust in housing
transactions through the creation of clear criteria and systematic processes.
The NHF also has the vision to make homeownership a far-off dream turn into a
realistic and achievable objective among thousands of Ghanaian families.
Funding Organization and Financial Dynamics.
The success of the National Homeownership Fund is largely
based on its funding structure and financial architecture. The fund is usually
funded by a blend of government contribution, development finance contribution
and possibly by the private sector funding. Such portfolio investment makes it
more resilient and less dependent on one source.
One of them is through the issuance of low-interest loans or
guarantees to the participating financial institutions. The NHF makes it
cheaper to receive capital by lenders so that they can provide more favorable
mortgage terms to first-time buyers. Some of the models also allow the fund to
finance partial down payment help, which significantly reduces the initial cost
of buyers.
The other feature is credit enhancement. The NHF reduces the
default risk among the lenders through guarantees or risk sharing arrangements.
This promotes lending of funds to borrowers who would have been considered to
be marginal in the traditional risk-based approach. The fund lowers the risk of
access to finance in a way that does not jeopardize financial stability.
The transparency and accountability play an important role
in ensuring investor and public confidence. Efficient utilization of the funds
is enforced by clear reporting structures, independent audits and stringent
eligibility requirements. An effective financial framework does not only ease
home ownership but also draws more houses on the wider housing finance system
in Ghana.
Application Process and Eligibility Criteria.
To attain its goals, the National Homeownership Fund must
have clear sets of eligibility criteria. The fund mainly focuses on first-time
homebuyers that satisfy income requirements and have steady jobs or steady
income. The applicants are either obliged to show proof of their employment
status, income levels, and credit history.
The emphasis on first-time buyers will make sure that the
resources are concentrated on the first-time purchasers and not on investment
in people who already have a property. This is a strategy that boosts equity
and maximises social impact. The income caps are useful in making sure that
support is only given to people who really need it and not taken by those who
are more economically advantaged.
The procedure of the application is meant to be user
friendly but well organized. The potential beneficiaries make an application to
the participating financial institutions that determine the credit worthiness
in consultation with the directives of the fund. After it is approved,
financial assistance is extended to the buyers in the form of the reduced
interest rates, guarantees or down payments.
Creating public awareness campaigns is one of the important
measures to guarantee a wide participation. Easy understanding of eligibility
requirements, documentation process, and schedules can help to decrease
misinformation and create trust. The effective processing systems also avoid
delay that may deter the applicants.
The NHF builds trust in beneficiaries and financial partners by upholding clear and fair eligibility requirements, which will guarantee the sustainability of the initiative long term.

Economic and Social Effects of an Increased Homeownership.
Developing the homeownership potential with the help of the
National Homeownership Fund has considerable economic and social advantages. On
a personal basis, home ownership ensures stability, security and a chance to
accumulate wealth in the long run. Owning property enables families to
accumulate equity, which could be used to fund education, business or to save
towards their retirement.
The macroeconomic level is that more housing is demanded,
which increases construction activity that provides jobs at both ends of the value
chain that includes the architects and engineers and the artisans and
suppliers. Housing investment has a multiplier effect that promotes the growth
of the economy. The NHF helps more people to access mortgages, which further
increases financial inclusion and the banking sector.
Homeownership creates more solid communities socially.
Well-established neighborhoods promote civil activities, better education, and
social unity. Safe housing helps to decrease vulnerability and leads to a
better health and well-being.
But sustainable impact is based on wise risk management. A
credit bubble or improper screening of the borrowers might result in financial
instability. Close observation and responsible lending is thus necessary.
In general, the NHF can create the far-reaching ripple
effects in the entire economy of Ghana and society, which supports the
significance of inclusive housing finance.
Public-Private Partnership and Institutional Collaboration.
The effectiveness of the National Homeownership Fund (NHF)
depends greatly on a close cooperation between government agencies, financial
institutions, property developers and regulatory agencies. By establishing
successful partnership with the private sector, the fund can consolidate
financial resources, technical resources, and administrative resources as well
as spreading risks among various stakeholders. This is a shared-responsibility
model that enhances the viability and sustainability of the initiative.
Mortgage lenders and banks are key operationally involved as
they have to administer loans within the structure of the fund. They make
evaluations of applicants, pay and arrange repayment arrangements according to
stipulated conditions. Their involvement is such that funding gets to qualified
first-time homebuyers effectively and without any wastefulness. On the other
hand, the developers play their part in building affordable housing units that
are within the set standards of price, durability and quality. They are able to
provide affordable but decent houses and this directly affects the effect of
the fund on the accessibility of housing.
Regulatory agencies make sure that the financial
regulations, policies on housing and consumer protection standards are adhered
to. Proper management reduces chances of misappropriation and protection of
both the government expenditure and company capital. On the institutional
level, coordination leads to efficiency. Standardized land administration
mechanism, the shortening of property registration timelines and standardized
valuation criteria decrease the delays in the bureaucracy and the cost of transactions.
When the institutions are harmonized, the duration taken to implement projects
reduces and implementation becomes more reliable.
Strategies of Risk Mitigation and Problems.
Despite the fact that the National Homeownership Fund (NHF)
is a promising channel of accessing homeownership, it has a number of major
challenges which may influence its future performance. One of the major
concerns has been the macroeconomic instability. An escalation of inflation and
changes in the interest rates have the direct impact of affecting the
affordability of mortgage by placing an extra strain on repayment of the
beneficiaries in terms of monthly payments. Also, fluctuation in currencies may
increase the prices of imported construction materials hence the overall
housing prices and this may worsen loan sustainability among borrowers.
Another important problem is credit risk. In case the
screening and credit checks of borrowers are not done carefully, the rate of
default will increase, posing a threat to the financial stability of the
involved institutions and affecting the confidence of the fund. Strong
underwriting standards, comprehensive verification of incomes, and properly
developed risk-sharing arrangements between the fund and the lending
institutions are necessary to take care of this risk. These are the safeguards
toward the balancing of the increased access to credit and the responsible
lending practices.
There is also the constraint of supply-side. Unless the
affordable housing units are produced at the same level as the demand is
injected in the fund, there is the possibility that the property price will go
up making it less affordable. Bringing together the same aims in the housing
development through collaboration with the developers and simplified land
processes are required to prevent such malfunctions in the market.
The effect of the fund can also be limited by administrative
inefficiencies and lack of awareness of the population. Constant monitoring and
good data gathering practices and feedback of stakeholders are essential in
early detection of emerging problems. The proactive management of risks will
eventually increase the resiliency of the NHF, securing the beneficiaries and
ensuring the stability of the financial system, in general.
Future Outlook and Implications of Policies.
In outlook, the National Homeownership Fund (NHF) can
significantly change the housing finance in Ghana. It sets the stage to have a
more inclusive and sustainable housing system by instilling a systemic support
of first-time homebuyers. The fund establishes a sustainable structure that can
be extended to provide more people with access to homeownership as opposed to
relying on interventions that are not long-term. The future development of the
NHF may include the attraction of the private sector including the
collaboration with banks, pension funds, and impact investors. Increasing the
sources of funding would increase its capacity and sustainability in the long
run.
Efficiency and transparency could also be enhanced by
incorporating the use of digital platforms in the application and approval
process. Submission, verification and tracking online systems would minimize
the administrative bottlenecks and the processing times. Simultaneously, more
robust data management systems would enable the efficient performance
monitoring and risk assessment and evidence-based policy changes.
The key to the long-term success of the fund will be policy
coherence. Precisely matching the NHF with land reforms, urban planning
strategies, and development of the mortgage market will provide an enabling
ecosystem to maximize the impact. Policies will be reviewed and improved
continuously to give responsiveness to the changing market conditions and
housing market trends.
Provided it is adopted successfully, the NHF would be of
relevance to other upcoming economies aiming to increase homeownership in a
responsible manner. Its success in the future will rest on strict governance,
long-term financing framework, and its commitment to continue making its
services affordable to target beneficiaries.
Conclusion
The National Homeownership Fund is also one of the major
measures to tackle the crisis of affordability of housing in Ghana. It provides
a new hope to first-time homeowners by reducing financial barriers, mobilizing
blended capital and encouraging institutional cooperation. Although there are
challenges, it can be instilled with long lasting effects through proper designing
and responsible execution.
Homeownership is not just a monetary event, but it is a source of stability, integrity, and wealth. With the help of the NHF, Ghana is a step further to rendering that foundation available to a larger portion of the population, which strengthens the communities and the state economy in general.
-3dkuLgKhRD.jpg)
-49HupTvwDD.jpg)
LEAVE A REPLY