

financing-tools-and-incentives-for-developers
Financing Tools and Incentives for Developers in Missing Middle Housing
Introduction
The housing crisis gripping cities across North America has spotlighted a once-overlooked solution: missing middle housing. These modest, human-scaled buildings—duplexes, triplexes, fourplexes, courtyard apartments, and townhomes—offer a sweet spot between single-family homes and large apartment complexes. They increase density without overwhelming neighborhood character, support walkability, and expand housing options for middle-income families.
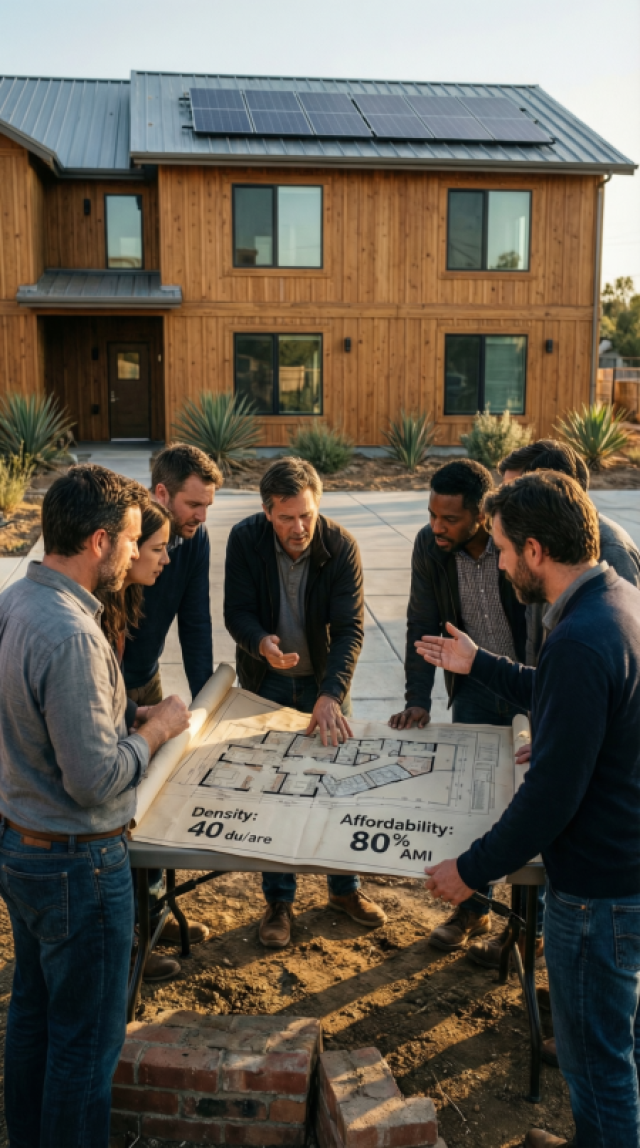
Yet despite their clear benefits, missing middle housing remains underbuilt. Why? Because traditional development economics often fail to support small-scale, incremental projects. This is where Financing Tools and Incentives for Developers become essential—not just helpful, but foundational to unlocking this housing typology at scale.
Cities, states, and community organizations are increasingly recognizing that regulatory changes alone won’t suffice. Without targeted financial support, even the most progressive zoning reforms stall in practice.
That’s why a new generation of programs is emerging—designed specifically to make missing middle housing financially viable. These Financing Tools and Incentives for Developers address capital gaps, reduce risk, lower soft costs, and improve returns for builders willing to pioneer this space.
Financing Tools and Incentives for Developers: The Unique Financial Hurdles
Missing middle projects typically fall into a “Goldilocks gap”: too small to attract institutional investors, yet too complex for standard single-family construction loans. Lenders often view them as higher risk due to unfamiliarity, uncertain rental demand, or fragmented permitting processes.
Land costs in desirable neighborhoods further squeeze margins, especially when affordability requirements are layered in. For small or local developers—who are often best positioned to build sensitively within existing communities—these barriers can be insurmountable without external support.
This is precisely where Financing Tools and Incentives for Developers step in. By offsetting upfront costs, improving cash flow, or guaranteeing portions of debt, these mechanisms transform borderline projects into bankable ones. They don’t just make development easier—they make it possible.
Public Grants and Low-Cost Capital Programs
One of the most direct forms of support comes from public funding. Municipalities and state housing agencies are launching grant programs and low-interest loan pools explicitly for missing middle housing.
California’s Affordable Housing and Sustainable Communities (AHSC) program, for example, funds infill projects near transit—including small multifamily buildings—that reduce vehicle miles traveled. Oregon’s Middle Housing Land Acquisition Fund provides grants to nonprofits and mission-driven developers to acquire land for duplexes through simplexes.
These programs often include technical assistance alongside capital, recognizing that access to money alone isn’t enough. When paired with streamlined approvals or pre-approved designs, they significantly de-risk early-stage development.
Such initiatives represent a powerful category of Financing Tools and Incentives for Developers, particularly for those without deep balance sheets or prior multifamily experience.
Zoning Reform as an Economic Catalyst
While not a direct cash infusion, regulatory reform functions as a critical financial lever. Legalizing missing middle housing by-right—without discretionary reviews or variances—slashes entitlement timelines and legal fees. Cities like Minneapolis, Portland, and Berkeley have done this citywide, instantly making thousands of lots eligible for gentle density.
Moreover, density bonuses tied to affordability (e.g., allowing a sixth unit in exchange for one income-restricted unit) improve pro formas without requiring public subsidy. These policy shifts may seem administrative, but they translate into real savings—often tens of thousands of dollars per project.
In this sense, modernized zoning is itself a form of Financing Tools and Incentives for Developers, reducing friction and increasing predictability.
Property Tax Abatements and Fee Waivers
Operating costs can sink a marginal project, especially in the first few years before full occupancy. To ease this burden, many cities offer property tax abatements for 5–15 years on new residential construction.
Philadelphia’s 10-year tax abatement, though controversial, has demonstrably spurred infill development, including missing middle types. Newer versions of such policies now include affordability triggers or geographic targeting to ensure equitable outcomes.
Similarly, impact fee waivers or reductions for small-scale developments lower hard costs. Seattle, for instance, waives school impact fees for projects with fewer than four units. These fiscal reliefs, while modest individually, collectively enhance feasibility. They are increasingly recognized as vital components of Financing Tools and Incentives for Developers working on tight budgets.
Specialized Loan Products from Mission-Driven Lenders
Traditional banks rarely offer construction loans under $1 million, pricing out most missing middle projects. Enter community development financial institutions (CDFIs), local housing trust funds, and state housing finance agencies. These entities provide flexible, patient capital tailored to small-scale housing.
Washington State’s Housing Finance Commission runs a “Missing Middle Pilot” offering subordinate loans at below-market rates. The Local Initiatives Support Corporation (LISC) and Enterprise Community Partners deploy blended capital stacks—combining grants, senior debt, and mezzanine financing—to fill gaps.
These products feature longer amortization periods, interest-only phases, and covenants aligned with community goals. They exemplify how innovative lending models serve as indispensable Financing Tools and Incentives for Developers committed to equitable growth.
Public Land Disposition and Land Banking
Land acquisition is often the largest line item in a development budget. Public land banks—entities that hold and repurpose vacant or tax-delinquent properties—can dramatically lower this barrier. By selling or leasing land below market value to qualified developers, cities turn idle assets into housing opportunities.
In Detroit, the Detroit Land Bank Authority prioritizes local builders for side-lot and infill projects, often requiring missing middle designs. Atlanta’s Land Use Department offers long-term ground leases for affordable housing on city-owned parcels.
These strategies reduce developer risk and ensure public benefit. As such, strategic land use is a high-impact form of Financing Tools and Incentives for Developers, leveraging real estate equity rather than cash subsidies.
Technical Assistance as Embedded Capital
For many small developers, the biggest hurdle isn’t money—it’s know-how. Navigating layered financing, design standards, and compliance can be overwhelming. That’s why leading programs bundle capital with hands-on support.
Pre-development grants covering feasibility studies, architectural renderings, or entitlement strategy effectively act as risk mitigation.
Nonprofits like Habitat for Humanity and Grounded Solutions Network offer builder training focused on small multifamily. State housing departments run “developer academies” to build local capacity.
This blend of knowledge and capital ensures that Financing Tools and Incentives for Developers reach those who need them most—and that projects actually get built, not just planned.
Private and Philanthropic Innovation
Beyond the public sector, private capital is beginning to see opportunity in missing middle housing. Impact investors and family offices are funding “naturally affordable” units—those priced accessibly due to efficient design, not deep subsidies.
Foundations like MacArthur and Ford have launched loan guarantee facilities to backstop CDFI lending, enabling better terms for developers.
These partnerships expand the capital ecosystem and introduce creative risk-sharing. A philanthropic guarantee might cover 20% of a loan loss, allowing a lender to offer lower rates.
Though still nascent, such models show how Financing Tools and Incentives for Developers can emerge from cross-sector collaboration, not just government alone.
Real-World Success Stories
Proof lies in practice. In Arlington, Virginia, the county’s Affordable Dwelling Unit program offers expedited review and density bonuses for missing middle projects with affordable units.
One local builder used these Financing Tools and Incentives for Developers to replace a single-family home with six townhouse units—achieving both market returns and community benefit.
In Minneapolis, after citywide legalization of triplexes, a nonprofit launched the “Triplex Fund,” combining low-cost loans with standardized plans. Within two years, over 40 new triplexes were underway—many led by first-time, BIPOC developers previously excluded from traditional finance. These cases prove that when Financing Tools and Incentives for Developers are accessible and well-designed, production follows.
Equity, Accessibility, and Program Design
Not all incentives are created equal. Many programs suffer from complex applications, limited outreach, or eligibility criteria that favor large firms. To truly expand the builder pool, Financing Tools and Incentives for Developers must be simple, well-marketed, and inclusive.
This means offering bilingual materials, accepting non-traditional credit histories, and providing application coaching.
Furthermore, safeguards against displacement are crucial. New missing middle housing should stabilize—not destabilize—neighborhoods.
Linking incentives to anti-displacement measures (e.g., right-to-return policies or tenant protections) ensures that Financing Tools and Incentives for Developers serve existing residents, not just newcomers.
Scaling What Works
The good news? We already know what works. From land banks to tax abatements, CDFI loans to zoning reform, the toolkit exists. The challenge now is scaling these Financing Tools and Incentives for Developers beyond pilot programs and demonstration projects. This requires dedicated funding streams, interagency coordination, and political will.
State legislatures can play a key role by authorizing local option taxes for housing trust funds or mandating inclusionary zoning with density bonuses. Federal programs like the Low-Income Housing Tax Credit (LIHTC) could be adapted for smaller projects.
Every layer of government has a part to play in expanding access to Financing Tools and Incentives for Developers.
Conclusion: Building the Future, One Duplex at a Time
Missing middle housing isn’t a niche experiment—it’s a necessary evolution of our neighborhoods. But its success hinges on economics as much as aesthetics. Without deliberate financial support, even the best-intentioned policies will yield little on the ground.
That’s why Financing Tools and Incentives for Developers must be central to any serious housing strategy.
From public grants and tax relief to flexible loans and land access, these tools lower barriers, share risk, and reward innovation.
They empower small builders, promote equity, and accelerate production. Most importantly, they turn vision into reality—brick by brick, unit by unit.
As more cities embrace gentle density, the demand for smart, scalable finance will only grow. The time is ripe to invest not just in housing, but in the developers who build it. With the right mix of Financing Tools and Incentives for Developers, the missing middle can finally take its place as a cornerstone of inclusive, sustainable communities.
And as we look toward 2026 and beyond, the continued refinement and expansion of Financing Tools and Incentives for Developers will determine whether missing middle housing remains a promising idea—or becomes the new normal. The path forward is clear: build the financial infrastructure, and the housing will follow. After all, every great neighborhood starts with the right Financing Tools and Incentives for Developers.
-5yCS4OoVBg.jpg)





LEAVE A REPLY