

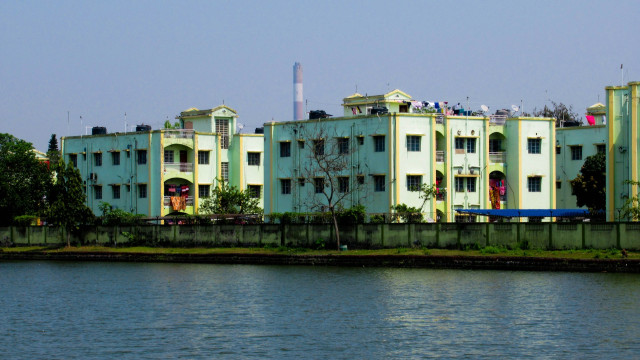
Bangladesh Needs 10.5M Homes by 2030: The Affordable Housing Crunch Explained
Bangladesh is on the verge of a urban change. Being one of the South Asia regions with the fastest population growth rate, urban migration, and socio-economic needs, the nation is experiencing a very serious setback as it will have 10.5 million housing deficit by 2030. This is not simply a statistic, but rather, the expression of the severe housing crisis that existed in millions of families, in the rural and urban setting of Bangladesh. With the government moving on with Vision 2041 and an intention to become a middle-income nation, as well as other developmental objectives, it is no longer something that can be left unresolved instead resolving the problem of affordable housing is something that is needed.
Housing deficit in Bangladesh is actually brought out by a very complicated combination of issues such as population growth, unplanned urbanization, increasing price of land, limited access to formal sources of finance and poor town-planning. In case of small and medium population earners and those in urban areas such as Dhaka, Chattogram and Gazipur, a good, affordable home is an uphill task. Slums keep spreading, congestion levels are rising to new extremes and many people do not have ready access to basic amenities like sanitation, clean water and electricity.
The implication of this crisis goes way past shelter. It has impacts on health, productivity, education and general social mobility. The need to provide 10.5 million homes in such a short period demands the introduction of new policy, the involvement of the private sector, and the deployment of such financial instruments as housing REITs and a new emphasis on sustainability and inclusivity.
What are the main aspects of this national emergency and what needs to be done to overcome one of the greatest challenges in the history of Bangladesh development?
Urbanization and Inequality as the Roots of the Crisis
The rapid and yet unplanned city or in other words urbanization lies at the heart of the affordable housing deficiency in Bangladesh. There has been a historical and unparalleled rural-urban migration in Bangladesh in the last thirty years. Cities are places where people go in order to get better jobs, education, and health. Urban planning has not moved with this change in population however. Such cities as Dhaka now house more than 20 million people and almost 40 percent of them live in informal or semi-formal dwelling patterns.
This immigration has strained the available facilities. Shortage of land in the best places within the city centers has pushed the prices to the stratosphere and it is becoming hard to find a nice shelter to put up in by the ordinary family. All the attention is on high-margin buildings like luxurious apartments and business premises leaving out the poor and the middle income population. The limited available affine housing projects are either not well done, most of them are far away from the hub of economic activity, or are lacking basic facilities.
In addition, income inequality is increasing the affordability gap that exists in housing. Although Bangladesh has achieved some remarkable advances in terms of poverty reduction, still a great part of the population is exposed to economic disturbances. Saving up to buy a house is impractical to such families. In most instances they have to resort to the informal housing conditions- consisting of slums, rooms or shacks and they become vulnerable to health hazards, eviction as well as social exclusion.
The informal housing sector remains a thriving sector especially in the urban fringe. However, such settlements do not have a legal status, infrastructure development, or security. The problem will continue and worsen unless a thorough approach, incorporating affordable rental housing, land reforms and access to formal housing finance are incorporated. Urban inequality is not merely a social problem thus it is also spatial since opportunity is defined where a person lands and the conditions that surround him.
Acute Shortage of Land, Regulatory Issues and Cost of Building Construction
The crisis in housing in Bangladesh is not only a matter of demand; but a matter of extreme scarcity in the supply. The significant impending challenge is land scarcity especially in an urban setting. The central part of land in the Dhaka and other large cities has been built on or is currently being disputed, or else its price is prohibitively expensive to affordable housing developers. Acquisition of land can be very slow, bureaucratic as well as corrupt unlike in England where it takes years to add in the cycle of housing.
In addition, the zoning codes and the obsolete building regulations inhibit innovation in housing patterns and vertical developments. Taking one example, developers in the center of major cities are blocked by height limits and low Floor Area Ratios (FAR) so that they cannot develop at height where an up-rise would offer more housing on a small area. Such rules also act to disincentives the use of modular or pre-fabricated construction methods or other methods that are quicker and cheaper.
To make the situation worse, there is an increasing prices of construction materials. Inflation rappers have hit the world over, supply chain issues, and domestic logistical weaknesses, have contributed to the explosion of price in cement, steel, and other fundamental materials. In the case of developers operating in narrow margins especially in the affordable housing programs the increase in costs can render the new developments economically unacceptable.
Moreover, there is low availability of construction funds. Commercial banks lend large developers money but in most cases, small affordable housing builders have a problem in terms of satisfying the collaterals. The interest rates are not that low and risk-averse banks opt usually to finance established projects which would give them higher returns than building affordable houses.
The supply off of the affordable housing equation will continue to be constrained without change in land governance, building regulations and financial instruments to support the developers. The outcome is a mismatch, as millions of people require houses, yet developers are not able to deliver them cheaply, promptly, and in large numbers.

The Financing Gap: Why Mortgages and Loans Aren’t Reaching the Poor
The inability of low- and lower-middle-income population to access housing finance, perhaps, is the most glaring hurdle of the overall house crisis in Bangladesh. Most countries have loans systems such as long-term mortgaging which allows an individual to own a house with ease. In Bangladesh however, it is mostly a preserve of the rich and upper-middle classes. The formal ratio of mortgage-to-GDP is low at less than 5%, among the lowest in the region.
This is so because of a number of reasons. To begin with, risk appetite of most financial institutions in Bangladesh is low. Banks usually insist on legal income documents, large collateral and steady employment history, which most poor families, informal employees and the self-employed would not be able to match. These types of households are not able to access formal housing market without access to long term capital at an affordable rate.
Second, the rate of interest on home loans is very high in comparison with the levels of income. Most borrowers also do not want to sign up with long periods of repayment (decades) even with subsidies or refinancing arrangements (believe me, some people do not like to live in fear or unemployment). The issue is further aggravated by the education and financial literacy level of borrowers that in the majority of cases is not high enough to make educated decisions: most of the potential homeowners are unaware of how to apply to a loan program, of how to compare and contrast financial products.
In Bangladesh, micro finance institutions are operational; however, in general, they do not provide long term housing loan. They specialize in small working capital loans which can be of assistance in betterment of livelihood but can never sustain the expenses of buying a house or constructing it.
This gap requires ingenious solutions. They are government-subsidized mortgage backings and online loans where alternative credit ratings are used by lending institutions and housing microloans, which provide mortgage loans with ample terms. Besides this, Real Estate Investment Trusts (REITs) where they accumulate funds of individual small investors to fund housing projects are also becoming interesting as a means of narrowing-down the funding gap. Nevertheless, they are hardly developed within the Bangladesh setting, and they need a legal and regulatory framework that will be powerful enough to support it.
Unless the housing finance structure is made egalitarian and unified, the dreams of homeownership would never become a reality by the very populace that is in dire need of one.
Policy, Public Private Partnerships and the State Role
To address the affordable housing crisis in Bangladesh, one needs not only good intentions but much structural policy change, good governance, and incentives to be innovative. Luckily, at least a partial improvement has been achieved. One of the priorities of the National Housing Policy relates to inclusive urban development and safety and shelter provision to all people and vulnerable population categories. Implementation is however very slow, disjointed and uncoordinated.
The state plays a very important role not merely as a regulator but also as an enabler and an investor. The growth of Public-Private Partnerships (PPPs) in affordable house is one promising sphere. The government through its private developers, financial institutions, and the civil society organizations should be able to use the power of the private capital with the guarantee that social goals are reached. As an example, the state can offer some subsidized land, tax breaks or infrastructure incentive in exchange of guaranteed share of the housing units priced at an affordable price.
Moreover, the inclusiveness has to be prioritised in urban planning led by government. It implies revising zoning policies in favor of high density and mixed income development, providing land on which social housing can be built, and incorporating housing with transport nodes and employment centres. Such planning was necessary, otherwise new affordable housing projects would have turned into ghettos isolated to the rest of the city.
Digitization is another important field. One could create the more transparent and digitally solid land registry to decrease corruption, accelerate the process, and secure the rights of ownership, particularly in the vulnerable populations, such as women and migrants. The security and achievement of the rental housing markets can also be facilitated through land titling reform and laws to protect the tenants.
Last but not least is the capacity building at a local level government? The municipalities usually do not have personnel, finances, and skills to implement large-scale housing programs. Scaling their solutions on the ground means the strengthening of their capabilities, which could be done through training, decentralization of funds, and integration of technology.
The eventual participation of the state is to create the environment in which affordable housing does not only become an option-but a priority and an asset as a common ordinary good.
A new vision of housing in Bangladesh, Technology and Innovation.
The solution to affordable housing crisis in Bangladesh is not just merely about solving what is wrong, but is also about what can be. Innovation and technology is the breakthrough which new avenues can open in 2025 and beyond to achieve the ambitious goal of 10.5 million homes by 2030.
The prospect of construction technology is one of the most launching ones. Use of pre-fabricated and modular housing can save time and cost of construction by a great margin. Local industries will be able to scale all these technologies through the facilitation efforts of the government. On the same note, it can be adapted by adopting 3D printing and green building materials to develop disaster resistant houses that are sustainable to the need of vulnerable climatic regions.
There is also the ability of digital platforms to improve transparency and efficiency. PropTech technologies are able to facilitate house purchasing procedures, locate the buyers with relevant houses, and deliver the information on construction activities in real-time. The blockchain technology is relatively new, but promises secure, tamper proof ownership records and transactions history of land.
Satellite images and urban analytics are provided via AI, and the information they convey will assist planners and developers in finding the best housing spot, monitoring the expansion of informal settlements, and properly deploying resources. An example is that smart mapping can display the areas with a poor infrastructure base to enable the governments to focus more on investing in that area.
However, innovation is not only technology-related--it is a way of thinking. It is also important to reconsider a housing model that incorporates the mechanism of the cooperative ownership, community-based construction, and rental flexibility. An affordable housing must not imply low quality housing/transitional measures. It ought to project status, safety and prospects.
In order to take up the task of 10.5 million households, Bangladesh needs to have the combination of radical policy and innovative design, funding, and acceptance, and the ambition and compassion. It is not only about the future of housing made out of concrete anymore, it is about ideologies that help people make the connection to live a better life.
Conclusion: A Race against Time, A Call to Action
Saying that 10.5 million homes should be built in Bangladesh and in 2030 without anything more will not make it happen- simply headlines are not going to make a solution. The main thing is to realize that further this is not merely a number, but a company humanitarian, economic, and social need. With each additional year that has elapsed without significant improvement, millions more are thrown into the pan of homelessness, poverty, and social marginalization. The housing crisis does not exist only in urban slums or slum areas where the poverty level is low as it affects very core of the economic position of the country in its stability, health and economic growth that might not be attained in future.
Poor-quality housing leads to worse health, lack of better education, and lack of upwards mobility. Living environments that are too crowded and not safe expose people to risks of disease, crime, and natural disasters, especially when living in climate-sensitive places. To attain the goal of the development, specifically to become a middle-income country, housing needs to be regarded important infrastructure but not as a market commodity alone by Bangladesh.
Not making an attempt to tackle this crisis on a systematic basis would be tantamount to compromising on the future of a country. The housing is not only about shelter but also dignity, productivity and inclusion. Each family left without an affordable and secure place to live in is a lost opportunity to contribute to the economy and sustainable society. It is pressing and we have a common responsibility. It is time to be decisive not tomorrow, but now.
This crisis cannot be solved in single solution. It demands teamwork- among government, private sector and the civil society as well as international partners. It takes some bravery to leave behind old policies and stagnancy. But most of all, it needs compassion: it needs to understand that behind each issue on housing numbers is a family that wants safety, security, and a place that they can call home. It is the possibility and the duty of Bangladesh to act. Not only is it possible with the right combination of political will, financial innovation, technology and social commitment to build 10.5 million homes, but it can also end as one of the success stories of this generation.
Also Read: Bangladesh- Homes and Loans= Decoding Bangladesh’s Housing Finance Sector
LEAVE A REPLY